
Key Takeaways
- A Cross-border payments vs digital banking primarily focuses on international transfers, multi-currency transactions, FX conversion, beneficiary management, payouts, and transfer tracking.
- A digital banking platform usually covers broader financial workflows such as accounts, cards, transfers, savings, budgeting, currency management, and everyday financial services.
- Fintech startups should compare target users, revenue streams, regulatory scope, product complexity, transaction frequency, and geographic strategy before choosing either business model.
Business Model Comparison Signals
- Cross-border payment platforms can monetize through transfer fees, FX spreads, business payment services, premium transfer features, and transaction-based pricing.
- Digital banking platforms can combine subscriptions, card-related revenue, account services, FX margins, premium plans, financial partnerships, and value-added banking features.
- Cross-border models concentrate on efficient movement of money between markets, while digital banking models aim to manage a wider and more frequent financial relationship with each user.
Founder Decision Insights
- Founders targeting remittances, freelancers, international businesses, or specific payment corridors may prioritize transfer speed, FX transparency, local payout methods, and multi-currency support.
- Startups targeting broader financial engagement should evaluate account management, cards, savings tools, recurring payments, budgeting features, compliance requirements, and banking integrations.
- Miracuves develops customizable fintech platforms with multi-currency transfers, FX workflows, digital accounts, payments, KYC, compliance controls, analytics, integrations, and admin management.
Fintech founders often face an early strategic decision: should the product focus on cross-border money movement, or should it become a broader digital banking platform?
Both models can create strong businesses, but they are not the same. A cross-border payment platform solves a focused problem: helping people and businesses send, receive, hold, convert, and manage money across countries and currencies. A digital banking platform usually covers a wider financial relationship, including accounts, cards, spending tools, budgeting, subscriptions, savings, business finance, and sometimes additional financial products.
The right choice depends on your users, corridor opportunity, regulatory path, available capital, product scope, and monetization strategy.
For founders, the goal is not to copy an existing fintech app blindly. The stronger decision is to understand which business model fits your market problem, then build the platform around that use case.
What Is a Cross-Border Payment Platform?
A cross-border payment platform helps users or businesses move money between countries, currencies, accounts, wallets, and payout methods.
It may support:
- Personal remittances
- Freelancer payments
- Business payouts
- Supplier payments
- Multi-currency wallets
- FX conversion
- Payment links
- Payroll and bulk transfers
- Recipient management
- Transfer tracking
- Wallet funding and withdrawals
- API or partner-led payment flows
This model works best when users have a repeated international money movement need. The product promise is usually built around transparency, transfer visibility, cost-efficiency, recipient convenience, and reliable payout execution.
A cross-border payment platform is focused, but it is not simple. It needs strong infrastructure behind the scenes: payment corridors, FX rate logic, payout rails, settlement records, fraud monitoring, admin controls, user verification, and reconciliation.
For readers who want a deeper explanation of the transfer flow, this guide explains how cross-border payment platforms work from onboarding to FX, payouts, and admin control.
What Is a Digital Banking Platform?
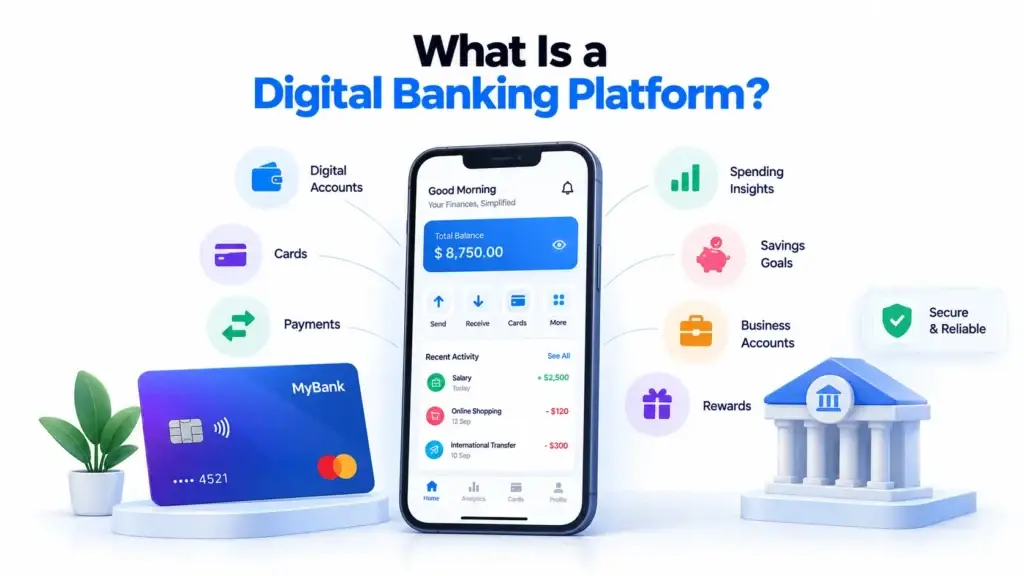
A digital banking platform is broader. It is designed to become part of a user’s everyday financial life.
Instead of solving only one money movement problem, it may support:
- Digital accounts
- Wallet balances
- Virtual or physical cards
- Domestic payments
- International transfers
- Budgeting tools
- Subscription tracking
- Spending analytics
- Business accounts
- Team permissions
- Savings or goal-based features
- Credit, lending, or investment modules where legally supported
- Rewards or premium plans
- Financial notifications
The main business logic is breadth. A digital banking platform tries to increase daily or weekly engagement by giving users multiple reasons to return.
That wider scope can create more monetization paths, but it also increases operational complexity. More modules usually mean more integrations, more support needs, deeper risk controls, broader compliance planning, and a larger product roadmap.
The Core Difference: Focus vs Breadth
The biggest difference between the two models is product focus.
A cross-border payment platform is strongest when it solves one painful money movement problem very well. A digital banking platform is strongest when it becomes a wider financial operating layer for the user.
Cross-Border Payment Platform vs Digital Banking Platform
| Comparison Area | Cross-Border Payment Platform | Digital Banking Platform |
|---|---|---|
| Core promise | Move, receive, hold, and convert money across countries and currencies. | Manage more financial activities inside one digital account experience. |
| Best first use case | One strong transfer corridor, remittance route, freelancer payout flow, or business payment need. | Everyday account usage, card spending, budgeting, payments, and wider financial engagement. |
| Revenue logic | Transfer fees, FX spread, business payments, payment links, payroll, API access, and payout services. | Subscriptions, cards, account fees, interchange, business plans, premium tools, and additional financial products. |
| Operational challenge | Corridor economics, payout rails, FX pricing, liquidity, transaction monitoring, and reconciliation. | Broader account infrastructure, card programs, support workflows, product expansion, and multi-service governance. |
| Compliance pressure | KYC/KYB, AML workflow support, transaction screening, corridor rules, and payout partner requirements. | Account operations, payments, cards, customer funds, risk controls, product-specific compliance, and partner rules. |
| Startup fit | Better for founders solving a specific cross-border payment or remittance problem. | Better for founders building a broader financial app ecosystem. |
Revenue Model: Which Platform Has Better Monetization Potential?
Both models can monetize well, but they monetize differently.
A cross-border payment platform usually monetizes around transaction volume and money movement. The business earns when users send, receive, convert, collect, or pay out money.
Common revenue streams include:
- Transfer fees
- FX spread
- Payment links
- Business accounts
- Payroll and bulk payouts
- Card usage where supported
- API and webhook access
- Premium reporting
- Partner payment workflows
A digital banking platform has broader monetization potential because it can create revenue across multiple product lines. These may include account plans, cards, premium subscriptions, business finance tools, spending products, value-added services, and additional financial modules depending on market rules.
The tradeoff is complexity. More revenue streams can look attractive, but every new financial product brings operational and compliance responsibility.
For founders comparing fee logic, FX spread, business payments, payroll, API access, and per-corridor economics, Miracuves’ payment platform business model page can help with deeper monetization planning.
Compliance Complexity: Focused Does Not Mean Easy
A focused cross-border payment platform can be easier to explain to users, but it still carries serious compliance and operational requirements.
Important control layers include:
- KYC workflows for individuals
- KYB workflows for businesses
- AML workflow support
- Sanctions-screening integration support
- Fraud monitoring
- Transaction risk flags
- Transfer limits
- Corridor-level rules
- Audit logs
- Admin permissions
- Refund and dispute workflows
- Reconciliation records
A digital banking platform may need an even broader compliance planning approach because it can involve account services, card usage, spending tools, fund storage, subscriptions, business finance, and additional financial products.
Final compliance depends on jurisdiction, legal review, licensed partners, payment corridors, product scope, integrations, and operating model. Software can support compliance-ready workflows, but it should not be treated as a substitute for legal and regulatory planning.
Product Scope: What Should Startups Build First?
A common mistake is trying to launch with too much.
A cross-border payment startup does not need to support every country, currency, business module, card program, and API flow on day one. It can start with one strong corridor or one clearly defined payment use case.
A practical launch sequence may look like:
- User registration and verification
- Recipient management
- Currency pair and FX quote
- Transfer creation
- Payment collection
- Payout tracking
- Admin dashboard
- Transaction monitoring
- Settlement and reconciliation
- Reporting and support workflows
A digital banking startup may need a broader foundation before users feel the full value. A practical launch sequence may include:
- Account creation
- Wallet or balance management
- Card or spending workflow
- Payment and transfer tools
- Transaction history
- Budgeting or analytics
- Admin and support dashboard
- Premium plan logic
- Business account workflows
- Additional financial modules in later phases
The difference is not only the number of features. It is the number of promises the platform makes to the user.
Founders planning wallets, transfers, FX, recipients, compliance workflows, and admin operations can review the cross-border payment platform features needed to support a focused remittance product.
For a deeper feature-level breakdown, this guide on money transfer app features explains the user, admin, wallet, transfer, and compliance workflows founders should consider.
Unit Economics: Corridors vs Ecosystems
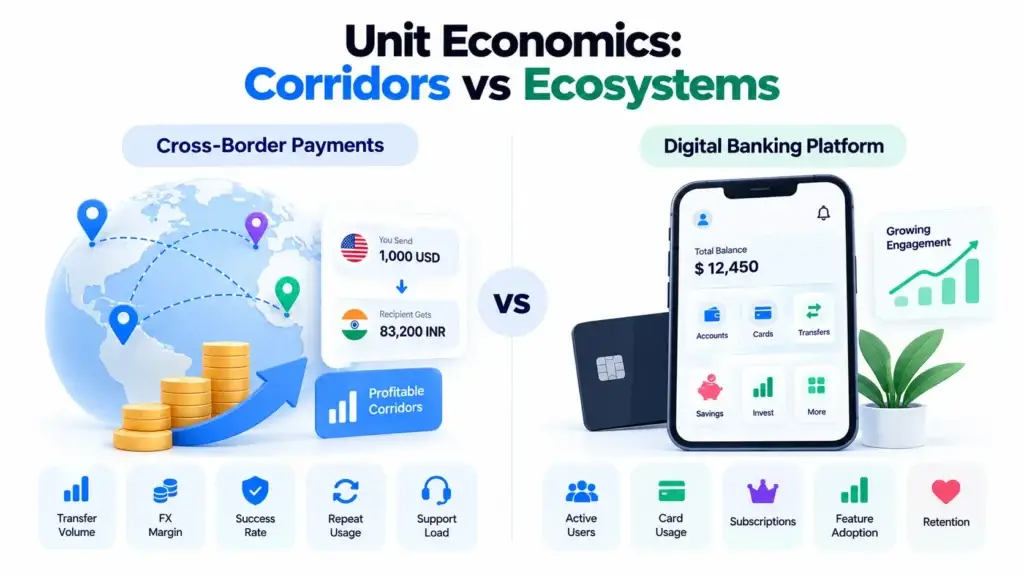
For a cross-border payment platform, unit economics are often corridor-specific.
One route may have strong user demand, reasonable payout cost, clear partner support, and repeat transfers. Another route may look attractive in market size but be difficult because of high rail costs, slow settlement, complex verification, low repeat usage, or support-heavy operations.
That is why a remittance founder should track:
- Transfer volume by corridor
- Average transaction value
- FX margin by route
- Payout cost
- Failed transfer rate
- Refund cost
- Support tickets per corridor
- KYC approval rate
- Repeat sender frequency
- Compliance review burden
A digital banking platform measures a wider set of signals:
- Active account usage
- Card activity
- Monthly active users
- Subscription upgrades
- Feature adoption
- Business account usage
- Support workload
- Retention by product line
- Revenue per user
- Cost to serve
The cross-border model is often about making one route repeat profitably. The digital banking model is often about expanding product engagement without losing operational control.
Founder Decision Signals: Which Model Fits Better?
Market Problem
Choose a cross-border payment model when users have a clear international money movement problem. Choose a digital banking model when users need a wider financial control center.
Launch Speed
A focused remittance platform can be easier to validate when the first corridor and user segment are clear. A broader banking platform usually needs more modules before the value feels complete.
Revenue Path
Cross-border platforms usually start with transfer fees, FX spread, and payout workflows. Digital banking platforms may expand into cards, subscriptions, premium accounts, and wider financial services.
Operational Complexity
Cross-border payments require deep control over corridors, rails, FX, KYC, AML, and reconciliation. Digital banking requires broader account, card, support, and product governance.
When a Cross-Border Payment Platform Fits Better
A cross-border payment platform may be the better starting model when your market has a repeated international transfer problem.
This can include:
- Families sending money across borders
- Freelancers receiving overseas payments
- Small businesses paying international suppliers
- Agencies managing contractor payouts
- Students receiving funds from family
- Import/export businesses managing currency movement
- Platforms needing marketplace payouts
- Remote companies paying teams across countries
This model works best when the startup can clearly answer:
- Which corridor are we solving first?
- Who sends money?
- Who receives it?
- What problem exists with current options?
- What fee, speed, payout, or transparency issue are we improving?
- What compliance workflows are needed?
- Which payout partners or gateways are required?
- How will we measure repeat usage?
The advantage is clarity. Users understand why they need the product.
The risk is margin pressure. Cross-border platforms must manage FX, rail cost, compliance cost, liquidity, support, and corridor-level profitability carefully.
When a Digital Banking Platform Fits Better
A digital banking platform may be the better model when users want one place to manage several financial activities.
This can include:
- Everyday digital accounts
- Card-first banking alternatives
- Youth or student banking
- Business expense management
- Multi-feature SME finance tools
- Digital wallet ecosystems
- Local banking alternatives
- Subscription-based finance products
- Financial super-app concepts
This model works best when the startup can create frequent engagement. If users only open the app once in a while, a broad banking product may struggle to justify its complexity.
The advantage is revenue diversity. The platform can monetize through multiple product lines.
The risk is execution depth. A broad product roadmap can stretch a startup too early if the team has not yet validated a core use case.
Can a Startup Combine Both Models?
Yes, but a hybrid model should be phased carefully.
A founder might start with cross-border payments, then add business accounts, cards, payment links, payroll, bulk payouts, and API access later. Another founder might begin with digital accounts and cards, then add international transfers after building trust and usage.
The mistake is trying to launch everything at once.
A phased approach works better:
| Growth Stage | Better Priority | What to Avoid |
|---|---|---|
| Launch | One clear use case, one audience, one corridor or core account flow | Trying to support every currency, card, business module, and partner integration immediately |
| Early traction | Improve onboarding, verification, transfer/payment success, and support | Spending heavily before product trust is proven |
| Repeat usage | Add retention workflows, saved recipients, business tools, reporting, or cards | Expanding features that users have not requested |
| Scale | Add new corridors, API access, premium plans, partner workflows, or advanced modules | Scaling operational complexity without admin visibility |
A hybrid can work when the platform has strong architecture, clear compliance planning, payment partner support, and enough operational capacity to manage the added scope.
Payment Infrastructure Should Match the Business Model
The platform’s payment infrastructure should match the business model from the beginning.
A cross-border payment product needs strong infrastructure for:
- FX quote logic
- Multi-currency balances
- Wallet funding
- Recipient validation
- Payment collection
- Payout routing
- Transfer tracking
- Settlement records
- Refunds
- Reconciliation
- Transaction monitoring
A digital banking product may need:
- Account creation
- Ledger logic
- Card integration
- Spending records
- Payment initiation
- Subscription billing
- Business account controls
- User roles
- Notifications
- Reports
- Support workflows
If your platform needs payment collection, wallet funding, payout routing, or gateway integrations, Miracuves’ payment gateway development service can support the transaction layer behind the product.
Common Mistakes Founders Should Avoid
Choosing the Broader Model Only Because It Looks Bigger
A wider product does not automatically create a better business. More modules can create more revenue paths, but they also increase compliance, support, and operational responsibility.
Ignoring Corridor Economics
For cross-border payments, each corridor has different rail costs, settlement timelines, support needs, risk signals, and profit potential. A blended view can hide weak routes.
Launching Without Admin Control
Founders need visibility over users, verification, transfers, fees, FX, payouts, refunds, risk flags, reports, and support workflows. Without admin control, operations become fragile.
Expanding Before the Core Use Case Repeats
Before adding cards, premium plans, advanced business tools, or extra corridors, founders should prove that users return for the first value proposition.
Founders can also review these mistakes fintech founders should avoid before planning corridors, compliance workflows, FX logic, payout operations, and product expansion.
How Miracuves Helps Founders Build Fintech Platforms Faster
Miracuves helps founders, fintech startups, and agencies launch ready-made and white-label fintech platforms with branded interfaces, admin dashboards, source-code ownership, payment workflows, and customization support.
For founders focused on international money movement, Miracuves’ cross-border remittance platform can help evaluate multi-currency wallet flows, FX transfer logic, payout workflows, admin visibility, and compliance-ready controls.
Businesses exploring related money transfer and payout models can also review Miracuves’ remittance app solutions for broader fintech launch paths.
If you are comparing budget and delivery scope, review Miracuves’ guide on remittance platform development cost. For vendor evaluation, this page on choosing a fintech development partner can help you understand what to check before selecting a team.
When the ready-made scope fits the rollout requirement, Miracuves can support 6-day solution delivery, helping founders move faster without building every onboarding, wallet, FX, payout, reporting, and admin workflow from zero.
Final Thoughts: Choose the Model Your Market Can Validate First
A cross-border payment platform and a digital banking platform can both become strong fintech businesses. The better model depends on what your users need first.
Choose a cross-border payment model when your users have a repeated international money movement problem. This path is stronger when the founder can identify a clear corridor, user segment, transfer pain point, and monetization logic.
Choose a digital banking model when your users need a broader financial experience and the startup has the product, compliance, partnership, and operational capacity to support multiple financial workflows.
The safest founder path is usually not the widest roadmap. It is the clearest first use case. Validate that, measure real behavior, strengthen operations, and expand only when the platform has earned the right to become broader.
FAQs
What is the difference between a cross-border payment platform and a digital banking platform?
A cross-border payment platform focuses on international transfers, FX, payouts, remittance, multi-currency balances, and business payments. A digital banking platform usually offers a broader financial experience with accounts, cards, spending tools, budgeting, subscriptions, and other financial services.
Which business model is better for fintech startups?
The better model depends on the market problem. A cross-border payment model fits startups solving a focused remittance, FX, payout, or international payment problem. A digital banking model fits startups building a broader financial ecosystem.
Is a cross-border payment platform easier to launch?
It can be easier to position because the use case is clearer, but it is not operationally simple. Founders still need KYC/KYB, AML workflow support, FX logic, payout rails, transaction monitoring, settlement, refunds, and reconciliation.
How do cross-border payment platforms make money?
They can earn through transfer fees, FX spread, payment links, business accounts, payroll and bulk payouts, cards where supported, API access, partner payment workflows, and premium reporting.
Can a fintech startup combine both models?
Yes, but it should be phased. A startup can begin with cross-border payments and later add accounts, cards, business tools, API access, or digital banking features. Launching everything at once can increase cost and operational risk.
What should founders build first?
Founders should start with the clearest use case. For cross-border payments, this may be one corridor, one user segment, transfer flow, FX quote, recipient management, payout tracking, and admin control. For digital banking, it may be accounts, wallet balances, cards, payments, and user engagement workflows.
Can Miracuves help launch a fintech platform faster?
Yes. Miracuves helps founders launch ready-made and white-label fintech platforms with admin dashboards, branded design, source-code ownership, payment workflows, and customization support. A 6-day launch may apply when the ready-made scope matches the rollout requirement.
Miracuves is an independent software development company. We are not affiliated with, connected to, sponsored by, or endorsed by any company or product named in this article.
Terms such as “X Clone” are used descriptively. It is how the software industry refers to building a platform with functionality comparable to a known service, and how clients search for it.
The entire design and codebase of our products is built by our own team. Our products contain no code, design, graphics, or content originating from any third-party website or applications.
All third-party names and marks referenced in this article are the property of their respective owners, referenced solely to identify the services discussed.