White Label Remittance Software - Money Transfer Platform You Own Outright
Built by Miracuves, this white label remittance software is a ready-made, white-label cross-border platform you own: Android and iOS apps, a browser PWA, an operator console and partner APIs, delivered as unencrypted source and set up on your cloud in six working days.
Senders hold balances in more than 30 currencies and see the fee before they confirm a conversion, while your staff change fees and FX margins in the console with no new release. The license to move money stays with you or your EMI, BaaS or sponsor bank, as do payout partners and pre-funded liquidity. A deeper compliance review stage or a referrals module is scoped and priced in writing, typically within 2-8 weeks.
Launch in 6 Days with
- Unencrypted Code
- Android App
- iOS App
- Browser PWA
- Ops Control Room
- Open APIs
StackFlutter · React · Next.js · Express · TypeScript · Prisma · PostgreSQL
Activity ticker, live
- Sender KYC approvedOnboarding
- USD → MXN transfer sentCorridors
- Settlement landed over SEPAPayout partners
- Screening hit sent to reviewCompliance
- Pay-by-link completedCollections
- Bulk payout batch approvedBusiness
- Prepaid card createdCards
- FX spread updated on corridorAdmin
- Sender KYC approvedOnboarding
- USD → MXN transfer sentCorridors
- Settlement landed over SEPAPayout partners
- Screening hit sent to reviewCompliance
- Pay-by-link completedCollections
- Bulk payout batch approvedBusiness
- Prepaid card createdCards
- FX spread updated on corridorAdmin
- 6Revenue Lines to Runtransfer fees, FX spread, card programs, payment links, business plans and API access
- 4Ways to Schedule a Sendone-off, scheduled, recurring and batch
- 0%Revenue Share With Miracuvesno per-transfer fee to us and no vendor kill switch
- 3Transfer Methodswallet to wallet, bank and card-to-wallet
- 6Days to Launchand if the delay is ours, we keep going free
- $12,999Paid Once, Not Rentedsource code yours, no per-seat fee, no monthly rental
Live in six working days, or we keep working free until you launch. Every build carries 60 days guidance, 6 months bug fixes and 12 months updates.Verify every figure
OrcaReserve Launched in Six Days
OrcaReserve took its own-branded transfer service from brief to a live platform in 6 days, quoting mid-market rates with visible fees and paying out over SEPA, ACH, SWIFT and local networks.
Bought Once, Not Billed Per Transfer
Rented remittance platforms charge a setup fee, then monthly or per-transaction charges on the vendor's servers; here the database, customer records and margins stay on infrastructure you control.
Card Data Stays With Your Processor
Payments run through the gateway connectors you contract, Stripe among them, and the platform keeps processor-issued tokens rather than card numbers on your servers.
01See it live
Try It Live
Remittance Software Demo - Sender App, Admin Dashboard & Screens
Open the demo before you commit: Miracuves hosts the sender app, the operator console and the web app, so you can walk through wallet, transfer and review flows the way your compliance and operations teams would. Map your corridors and user roles as you go.


Sender App - Android & iOS
Mobile money transfer app with multi-currency wallets, saved recipients, cross-border sends, cards, payment links and requests, an activity feed and account security settings.
- 1Check balances across currencies and wallets
- 2Walk through send, recipient and payment steps
- 3Try cards, money requests and the activity feed
test@wise.local | Test123!@#
Operator Console (Web)
Back-office control over remittance operations, users, KYC and compliance queues, fraud and risk alerts, transaction review, fee and platform settings, reports and day-to-day operations.
- 1Check user, tier and account controls
- 2Open the compliance, fraud and transaction review queues
- 3Try reports, platform settings and admin workflows
admin@wise.local | Demo123!@#
Web Platform for Senders & Businesses
Browser version of the product for wallets, transfers, invoices, payroll, analytics, organization accounts and finance operations, with separate views for each user role.
- 1Follow wallet, transfer and report journeys
- 2See how the browser app handles wider finance operations
Accounts, Wallet, ExchangeWatch the Tour
Money Transfer Software Video - Transfer Flows, Admin Console & Code Tour
Prefer a guided tour? Book a 30-minute call to map your corridors and launch plan.
Book a live walkthrough callWalkthrough of Every Screen
Money Transfer App Flows - Sender, Operator & Web Screens in Detail
See how each part of the platform behaves. Miracuves lays out every flow for senders, business users, admins and the web app, so your team can check each journey against your corridors and sign off on what is launch-ready.


Ask our team to walk you through the sender, business, admin or web journeys that matter most for your corridors and launch plan.
02Proof
Client Feedback
What Our Clients Say About Building With Miracuves
What founders, operators and product teams said after evaluating or launching white-label fintech platforms built by Miracuves.
“Working with Miracuves gave us a faster path to market than building a digital banking product from scratch. What stood out was not just the frontend quality, but the operational depth - especially around admin control, multi-currency flows, and product flexibility. We were able to shape the platform around our market instead of compromising on a generic script.”
“We reviewed multiple vendors before choosing Miracuves, and the difference was clear in the product maturity. The Wise-style experience was strong, but what really gave us confidence was the backend structure - accounts, transactions, business modules, and the Banking Core readiness. It felt like a product built for serious execution, not just demos.”
“Miracuves did not just deliver screens. They delivered a foundation we could grow with. The team understood that in fintech, admin controls, compliance posture, and scalability matter as much as design. That balance of speed, customization, and product clarity made the engagement much more valuable.”
Client Work
Remittance Case Study - Client Platform, Real Figures
How one operator used the Miracuves remittance platform to put its own money transfer brand in market, and what the build covered.
A white-label money transfer build for a US-based operator whose users send funds to recipients in other countries.

- Ship your own-branded transfer product that competes with Wise
- Plug in genuine FX rates plus payout networks that run on multiple rails
- Work through US compliance duties: KYC, AML and FinCEN reporting
- Recipient handling and transfer tracking, written from the ground up
- Hold full ownership of a remittance platform branded as OrcaReserve
- Quote mid-market exchange rates alongside a fee structure customers can see
- US senders can reach 50+ countries around the world
- A Wise-grade white-label clone tailored to OrcaReserve
- Exchange rate engine fed by live mid-market data
- Built-in module for KYC and AML compliance
- Local networks, SEPA, ACH and SWIFT as payout rails
- Dashboard for managing recipients and reviewing past transfers
- An admin panel to set rate margins and limits and to oversee transactions
“I wanted to compete with Wise under my own brand - Miracuves made that a reality. The exchange rate engine, compliance setup, and the speed of launch were beyond what I expected.”Chadi Boustani · Founder, OrcaReserve
03The product
The Basics
What Is White Label Remittance Software?
White label remittance software from Miracuves is a money transfer platform you buy once and operate as your own business. For background on how consumer transfer apps work, read our explainer. What you get here: sender and receiver apps, multi-currency wallets, corridor and FX rules, hooks for the payout partners you contract, KYC/AML queues and an operator console, all on infrastructure you control.
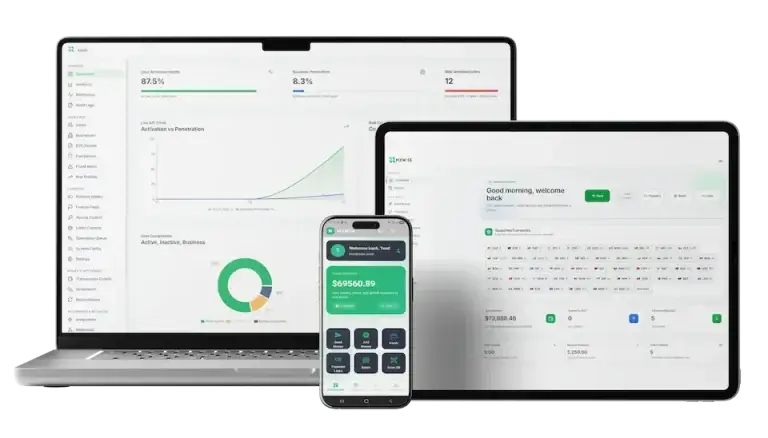
Android, iOS and Web Apps
One platform serves senders, operators and internal teams on mobile and in the browser, with a single backend behind every screen.
Your Brand on Every Screen
Your logo, colors, product name and positioning lead, while branding and platform settings are managed from the console instead of in code.
Core Modules Already Built
Wallets, transfers, invoicing, reporting, compliance queues and admin operations already exist in the codebase, so your team starts from a working base rather than an empty repository.
Under the Hood
What Is in the Remittance Source Code?
The remittance script is the source code and architecture that run your platform. Rather than writing each wallet flow, transfer module, compliance queue, report and admin control yourself, you start from an organized codebase you can rebrand, configure, extend and connect to your own corridors, payout partners and money transfer business model.
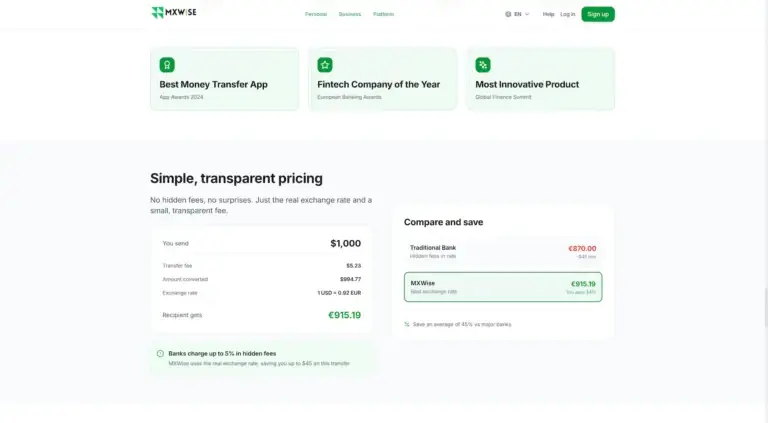
Buying the source code means you:
- 01Start from working code that is ready to configure for go-live
- 02Get it deployed in 6 days, not after months of build
- 03Begin with separate workflows for senders, businesses, admins and partners
- 04Add custom features, integrations, APIs and operational controls as your corridors grow
Briefly, then: white label remittance software gives you a working cross-border money platform with multi-currency wallets, transfers, operator controls and admin visibility, shaped around your corridors, users and business goals.
What It Does
White Label Remittance Software Features - Multi-Currency Wallets, Cross-Border Transfers & KYC
Miracuves' white label remittance software covers what senders, business users and operators expect from a cross-border money product, from multi-currency wallets and international transfers to invoicing, compliance queues and partner APIs. See the complete remittance feature list for every module.
Wallets in Many Currencies
Keep, track and manage balances in each supported currency from a single account.
- Balances in 30+ currencies
- Per-currency balances with reserved and frozen amounts shown
- Currency conversion that shows the fee before the user confirms
Cross-Border Transfers & Saved Recipients
Move money between wallets, bank accounts and saved recipients, with status visible at every step. Senders see the price before paying, and each route picks its own rail.
- Wallet to wallet, bank and card-to-wallet transfer methods
- Recipient records with bank details, IBAN, SWIFT and country
- One-off, scheduled, recurring and batch transfers
Payment Links, Requests & Bill Splitting
Collect and ask for money through flexible flows built for people and teams.
- Payment links carrying amount, currency and a description
- Payment requests with due dates you can track
- Shared-expense splitting that shows who has paid and who owes
Cards & Spend Limits
Card flows for online and in-store spend, with issuance and usage rules managed per card.
- Virtual card issuing and physical card request flows
- Daily or monthly spend limits on each card
- Card freeze and unfreeze plus a per-card transaction history
Freelancer Invoices & Client Records
Independent professionals can bill clients, get paid and follow their own financial performance.
- Invoices with line items, rates, taxes and status tracking
- A client directory with notes and activity history
- PDF export, quick re-invoicing and tracking of due dates
Business Accounts, Payroll & Bulk Payouts
Handle company finance with team access, payroll runs, batch transfers and approval steps.
- Team invites with permissions set by role
- Payroll runs, employee pay records and bulk payment execution
- Batch transfer upload, scheduling and status per line item
Reports, Analytics & Activity Logs
Follow user activity, financial results, exports and key metrics across the whole platform.
- Searchable logs covering transfers, cards, alerts and settings changes
- Dashboards for spend, savings, business figures and platform analytics
- Reports exported as PDF or CSV, plus scheduled report delivery
KYC, AML & Fraud Review
Verification, risk review, fraud alerts and screening hooks that feed the compliance program you operate.
- KYC and KYB review queues with verification checks and an audit trail
- Hooks for the sanctions-screening provider you contract, compliance alerts and AML/CFT case queues
- Fraud review, user risk profiles, transaction holds and anomaly flags
Admin Controls & Platform Settings
Set users, fees, branding, policies and system behavior from a single console.
- User administration, account status and tier management
- Brand settings, fee tables, feature flags and policy rules
- Admin audit logs, incident views and platform health checks
APIs, Webhooks & Partner Integrations
Connect partners and extend the platform through programmable access and event notifications.
- Access to an API marketplace with subscription management
- Scoped API keys with rotation, separate environments and usage tracking
- Webhooks with OAuth 2.0, delivery logs and test or retrigger tools
Crypto Wallets, L2 Routing & Advanced Modules
Optional modules for advanced users: crypto wallets, conversions and route-aware transfer options.
- Wallets for BTC, ETH and USDT
- Buy, sell and swap with a portfolio view
- L2 routing, bridge comparison, hedging tools and forward contracts
Security, Identity & Access Control
Guard users, sessions, devices and sensitive actions with layered access and security controls.
- Multi-factor sign-in via TOTP, SMS or email codes
- Trusted devices, biometric login and session management
- Role-based permissions, admin session tracking and login history
Each feature can be switched on, configured, reordered or extended to fit your business model, corridors, user types, compliance obligations and operating plan. Nothing is locked to a fixed template.
Money-Making Model
Revenue Models - Transfer Fees, FX Spread & Business Plans
A money transfer business needs two things working together: smooth flows for senders and clear ways for the operator to earn. Miracuves has the platform set up for both, with fee and margin models covering transfers, FX, cards, payment collection, business finance and API services.
Transfer fees, FX spread, card income and business subscriptions can be combined into one revenue model per corridor, set from the console rather than in code.
- 01
Transfer Fees & FX Spread
Charge on international sends and currency conversion through fee rules and spread pricing you configure.
- 02
Card Programs & Usage Fees
Earn from card issuing, card spend and limit tiers, with the card program run through your issuing partner.
- 03
Collections, Links & Money Requests
Earn on payment collection, business receivables and other activity driven by transactions.
- 04
Business Plans & Payroll Tools
Sell higher-value tools to business customers: payroll, bulk transfers, spend controls and reporting.
- 05
Partner API & Webhook Access
Charge technical partners and embedded-finance clients for programmable access, subscriptions or integration services.
- 06
Premium Finance Modules
Add premium tiers on top: crypto, forward contracts, hedging tools and advanced transfer routes.
| Revenue stream | How it is charged | Take rateTypical range | What sets the ceiling |
|---|---|---|---|
| Transfer Fees & FX Spread | A fee per send plus a margin built into the exchange rate you quote the sender. | Remitly: $1.6B revenue on $74.9B sent, about 2.1%-2.2%. Wise: 0.52%. | Policy and rivals. The UN goal is an average cost under 3%, against 6.36% measured in Q3 2025. A 1% US tax applies only to cash-funded sends. |
| Card Programs & Usage Fees | Interchange from the card network on each purchase, plus issuing and cash-withdrawal fees you set yourself. | US 2024 averages: 0.47% for regulated issuers, 1.21% for exempt issuers. | Issuer size. Large US issuers face a 21 cents plus 0.05% debit cap, so the size of your sponsor bank materially changes what the program earns. |
| Collections, Links & Money Requests | A percentage of each incoming card payment, deducted by the processor before funds settle. | Stripe India: 2% domestic cards, 3% foreign cards, plus 2% if converting. | Processor price lists. Foreign-card and conversion add-ons stack, so an international collection can cost 5% before you earn anything. Model the net, not the gross. |
| Partner API & Webhook Access | A platform fee charged to fintechs and banks that embed your transfer rails in their own apps. | 0.25% is Stripe Connect's starting fee when a platform sets its own rates. | Partner cost to build. Each embedded deal is negotiated against the buyer's own alternative, so treat any list price as an opening position, not a rate. |
How to read this. Remitly's revenue and send volume are in its FY2025 Form 10-K; the 2.1%-2.2% is our division and Remitly does not report it as a take rate. Wise's 0.52% is from its FY26 results. Card averages and the cap are the Federal Reserve's Regulation II data, the 3% goal is from the World Bank, and the tax is explained by CBH. Processor fees are from Stripe pricing. Nothing here prices your corridors or predicts your volume; the figures only anchor a spreadsheet.
White Label Remittance Software Revenue Model, Stage by Stage
Each corridor opens on the transfer fee and FX spread, and the operator console adds card programs, pay-by-link collection, business plans and metered API access as send volume grows.
One corridor
On the first one or two corridors, a per-transfer fee and the FX spread carry the business while repeat senders build trust, and every rate is changed in the console without a new release.
Repeat senders
Once the same senders pay the same recipients month after month, payment links, money requests and paid business plans for payroll and bulk payouts earn more from customers you already have.
Many corridors
Across a wider network, card programs run with your issuing partner, metered partner API access and premium modules such as forward contracts lift the margin beyond the transfer itself.
Fees and spread stay yours in full on every route, since Miracuves charges no per-transfer fee.
Back Office
Remittance Management Software Console - KYC Queues, Risk Review & Fraud Screening
A money transfer platform only pays off when the back office is easy to run. Miracuves includes a browser-based admin console for users, Identity checks and AML queues, fraud and risk alerts, transactions, reports, fees, branding and platform settings, all in one place.


Admin Console Strengths
- 01
Users & Accounts
See and manage users, tiers, account status and visibility on a single screen.
- 02
KYC, KYB & Compliance Queues
Review submissions, apply verification rules and work compliance cases from one place.
- 03
Fraud, Risk & Policy Rules
Work flagged activity, apply policy and act on higher-risk events quickly.
- 04
Transaction Review & Approvals
Watch money movement as it happens and step in when a rule calls for review. Checks run while the money can still be stopped, and every reviewer decision is kept on record.
- 05
Wallets, Fees & Finance Operations
Manage fee logic, settlement records, reconciliation, refunds and finance reporting.
- 06
Revenue & Analytics
Watch revenue, volume growth, active users and KPI movement over time.
- 07
Branding, Pricing & Platform Settings
Set product identity, pricing rules, feature access and operating modes from the console.
- 08
Organizations, Teams & Access Rules
Structured teamwork through role-based permissions, team spaces and invitations.
Web App (Sender Frontend)
Browser access for customers and operations staff: account views, statements, business finance workflows and full desktop use.
- Wallet, transfer, invoicing and reporting in the browser
- Wider business, freelancer and organization flows on desktop
- Admin and operations views alongside every customer journey
- A good fit for finance teams and multi-role use
Mobile Apps for Android & iOS
Wallet, transfer, card and personal finance flows on phones and tablets.
- Mobile coverage of wallets, transfers, recipients, cards, payment links, reports and admin tasks
- Runs on the same backend features as the rest of the platform
- Solid coverage of everyday money tasks for users
- Prepared for Android and iOS store release in your brand
04Scope delivered and the price attached
Deliverables
Included in the Package - Source Code, Mobile & Hosting Setup
Buying white label remittance software from Miracuves gets you the full stack, not a single app screen: customer apps for Android, iOS and web, multi-currency wallets, corridor and FX rules, KYC and AML review queues, an operator console and the APIs that tie them together, all with source code you keep. Outside the price sit the running costs of any transfer business: licenses at both ends or a licensed partner, correspondent and payout partners, pre-funded liquidity, identity and screening vendors, the people who run compliance, audits and hosting.
Android App
Android app carrying your brand for wallets, transfers, cards and everyday money tasks.
- Built on the same backend as every other surface.
- Covers wallets, transfers, saved recipients, cards, payment links and statements
- Ships with your logo, colors and app name for customer-facing use

iOS App
iOS app carrying your brand for the same core money journeys.
- Native coverage of wallets, transfers, recipients, cards, payment links and statements
- Reads from the same backend services as Android and web
- Part of the white-label stack you own after handover


Browser-Based PWA
Browser access for senders and businesses who would rather work on a desktop.
- Wallets, transfers, invoices, payroll, statements and daily operations in the browser
- Built for business, freelancer, admin and team accounts on larger screens
- The broadest of the three customer surfaces, suited to desktop finance work

Ops Control Room
One operator console for customers, KYC and AML queues, transfers, reports and settings.
- Where your operations and compliance staff run the business day to day
- Customers, KYC cases, fraud alerts, transfers, analytics, corridors and settings in one place
- Role-based views for operations, compliance and management staff
Connectors & Open APIs
APIs for automation and for connecting payout partners, banks and other outside systems.
- Endpoints for transfers, payments, compliance events, reports and operational triggers
- Webhooks, OAuth, API keys and usage tracking for partner connections
- Room to build custom connectors to the banking and finance systems you contract
Brand Setup & Theming
Your app name, logo, colors and screens configured to match your brand.
- Name, logo, colors and theme set from the branding settings
- Your brand on every customer-facing and operator-facing layer
- Feature visibility and presentation tuned to your market and rollout plan
$ deploy --to your-cloud Store Submission & Release Help
Hosting setup, go-live configuration, store submission help, plus technical docs & a full handover.
- Server and cloud setup with the provider you choose
- Assistance with your App Store & Play Store listings
- Technical documentation, a walkthrough & credentials handed to you
Help Beyond Go-Live
Bug fixes, help with configuration, and extended maintenance if you want it.
Pricing
How Much Does White Label Remittance Software Cost in 2026?
Most white label remittance software is rented: a setup fee, then monthly or per-transaction charges for as long as it runs on the vendor’s servers. With Miracuves you buy it once and keep it. The full money transfer platform costs $12,999 one time, with the source code handed over, deployment in 6 days, and no per-transfer platform fee paid to us afterward.
What shapes your final budget comes down to: the platforms you ship (Android / iOS / Web), how far you customize the brand, the operator console and compliance queues you need, the payout and banking partners you connect, any extra modules, hosting, and how much support you want after launch.
Professional
Ready-Made Platform, Owned OutrightA match if you: remittance startups, money transfer operators, exchange houses and fintechs that want their own cross-border platform, source code and customer data instead of renting one by the month.
What you see in the demo, carrying your brand and hosted on your own servers.
Ask About This PlanEnterprise
Custom Build & Extended RolloutA match if you: banks, larger payment companies, multi-corridor operators and partner-led programs that need deeper approval chains, extra integrations, custom modules or rollouts in tightly supervised markets.
Scoped and built around your corridors, partners and operating model.
Get a Custom QuoteWhite Label Remittance Software Development Cost in 2026
One $12,999 payment buys the full Miracuves remittance stack shown in the demo: Android and iOS sender apps, the browser PWA, the operator console, partner APIs and unencrypted source. Setup on your cloud takes six working days, and no transfer you process ever carries a fee to Miracuves.
What moves your total sits outside the software invoice
- Licenses at both ends of each corridor, or a licensed partner
- Correspondent and payout partners on every route
- Liquidity you pre-fund on each corridor
- Identity and screening vendors, plus the staff who run compliance
- Hosting, audits and your Apple and Google developer accounts
Custom work such as a deeper compliance review stage gets a written scope and price and typically runs 2-8 weeks, while banks and multi-corridor programs take the Enterprise route.
Renting keeps you paying for as long as you operate. Buying once means the code, the database and every customer record stay with you, and the plan you pick should follow your corridors, partners and growth goals.
Compare Your Options
Ready-Made White-Label Remittance Software vs Custom Development vs SaaS
Owning remittance software built by Miracuves, commissioning a build or renting a platform changes who keeps the code, the customer records and the fee on every transfer you process.
| Criteria | MiracuvesReady-Made White-Label Remittance Software | Custom Development | SaaS |
|---|---|---|---|
| Launch time | Deployed in 6 days, plus store review | Quoted in writing, typically 2-8 weeks | Sign up and start the same day |
| Upfront cost | $12,999 paid once | Quoted in writing for your scope | Low entry, then a recurring subscription |
| Source code ownership | Complete source, kept on your cloud | Yours if the contract assigns it | Stays with the SaaS vendor |
| Customization | Rework screens, corridors and fee logic | Unlimited, billed as extra build time | Settings, themes and plan limits only |
| Ongoing fees | No monthly or per-transaction charge | Maintenance billed by the agency | Monthly fees that rise with usage |
| Branding & app-store listing | Your brand on Android, iOS and web | Your brand, built from a blank screen | Vendor branding or a shared listing |
| Best for | Money transfer operators who want to own | Products no existing model can serve | Testing demand before you invest |
Same product, other editions: Wise Clone · Browse all Remittance solutions
Ownership
What White Label Really Means on This Platform
Typically, money transfer software sold as white label is a rental. The vendor bills an initial fee, followed by recurring or per-transfer charges, and everything runs on the vendor's servers. Miracuves draws the line elsewhere on its remittance platform.
Your service name, logo, colors and domain, the sender and receiver apps on iOS and Android under your own developer accounts, and every receipt, notification and email a customer sees. Corridors, fees and FX margins are settings in the admin console, so changing them does not mean a new release.
The full source code of the apps, the web platform, the backend and the admin console, plus its documentation. There is no license fee, no revenue share and no charge per transfer from us, and nothing stops you from changing, extending or redeploying it.
Owning the software does not authorize you to move money. Payment, e-money or money transmitter licensing at both ends of each corridor is held by your operating entity or by a licensed partner, along with the correspondent partners, the payout partners, liquidity funded in advance, and the bank that holds customer funds. Hardening around your deployment happens before launch. The software does not hold customer money at any point. A single installation serves one operator brand.
Practical Uses
Real-World Use Cases for White Label Money Transfer Software
Remittance software built this way is more than a send-money screen. A single Miracuves codebase serves different customer groups, revenue models and go-to-market plans, using wallets, payments, invoices, compliance queues, reports and operator controls.
Swipe · 6
Give individual customers multi-currency balances, money sent abroad, cards, payment requests and a modern app experience, all carrying your brand.
- Multi-currency balances for personal customers
- Transfers abroad, saved recipients and payment flows
- Cards, activity history and security settings in one app

Serve freelancers, consultants and independent professionals who need to invoice, manage clients, get paid, track income and keep records for tax.
- Invoices created, tracked and exported as PDFs
- A client list linked to each client’s payment history
- An earnings dashboard and records for one-person businesses

Focus on one geography, payment corridor, language market or operating model and fit it more closely than a broad, generic product can.
- A market-specific launch with your branded experience
- Transfer, wallet and compliance workflows tuned to the region
- Closer relevance to specialist customer groups and local business models

Put payroll, supplier payments, bulk transfers, invoicing, team permissions and spend tracking into one workspace built for companies.
- Team logins, spend limits and role-based permissions
- Payroll processing, batch payouts and sign-off chains
- Reports, cash-flow views and day-to-day company finance

Run the platform as the money movement layer behind your own product or partner network, using its APIs, webhooks, OAuth and connectors.
- API plans, usage tracking and key management
- Webhooks that push payment and compliance events as they happen
- OAuth and partner connections for embedded scenarios

Offer customers or companies crypto wallets, conversion, hedging tools, forward contracts and route-aware transfers in one advanced product.
- BTC, ETH and USDT wallets
- Buy, sell, swap and portfolio tracking
- Forward contracts, hedging tools and L2 routing

White Label Remittance Software Business Model: Three Ways to Run It
Every way of running this platform starts with one question, who holds the license on each corridor, and the build Miracuves hands over supports three answers.
Licensed operator
A money transmitter or exchange house runs the platform under its own authorization, prices each corridor with its own fees and FX spread, and keeps the full margin.
Partner-led
A startup without a license of its own operates through an EMI, BaaS provider or sponsor bank, launching on that partner's corridors while it proves repeat sending.
Embedded rails
A payments company or fintech exposes transfers to other platforms through partner APIs, webhooks and OAuth, and earns metered access fees from the products built on its rails.
Whichever model you pick, the code, the customer records and the margin on every send stay with you.
Money transfer software today reaches well past sending money. The same codebase can carry consumer remittance, freelancer payments, company operations, embedded finance and advanced products under one brand.
Book a Free Strategy Call2026 Opportunity
Why Launch Your Own Remittance Platform in 2026?
Senders and businesses now expect quick transfers, several currencies in one place, firm compliance checks and a clear view of every payment. Spreading payments, invoicing, compliance, reporting and team controls across separate tools adds friction and slows operations down.
In 2026, owning remittance software that Miracuves built replaces that patchwork with a single system you control: the workflows, the customer experience, the revenue and how far you scale.
01Own the Customer Relationship Instead of Renting Someone Else's Tools
Run your own platform and decide how wallets, transfers, payments, reports and customer relationships work, rather than leaning on systems you rent from someone else.
02Build a Money Movement Business Around Your Brand
Serve individuals, freelancers, companies and teams from one platform that combines wallets, invoices, payroll, cards, analytics and governance.
03Launch Sooner on a Proven Codebase
Skip months of building from nothing: deploy in 6 days and start testing workflows, uptake and real demand much earlier.
04Swap a Patchwork of Finance Tools for One Platform
Money movement, compliance, payroll, reporting and team permissions stop living in separate tools and sit together in one product.
05Serve Corridors, Regions or Verticals More Precisely
White-label software lets you shape branding, workflows, account types and positioning around one region, audience or business model.
06Earn Directly From a Product You Own
Transfers, payment collection, cards, business tools and API services become direct revenue lines inside a product you own.
Cross-Border Transfer Demand - What the Market Leader Reported for FY2025
Active customers Wise plc served in FY2025, across personal and business international payments.
Cross-border volume Wise plc moved in FY2025, up 23% year on year.
Year-on-year growth in Wise plc active customers reported for FY2025.
Underlying income Wise plc reported for FY2025, up 16% year on year.
Running your own money transfer platform is about more than moving money. It is the faster route to a business you control, with wallets, payments, compliance, reporting and operations in one place. Figures above: Wise plc, results for the financial year ended 31 March 2025.
Who It Serves
Industries & Operators We Serve
Money transfer operators running retail, business or partner-led models can use Miracuves' white label remittance software on whichever corridors their own licenses or licensed partners cover. Our software development for banking and financial services page gives the wider sector view, while custom work beyond this product sits under our fintech app development service.
one platformOne codebase
- 01RsRemittance Startups & Diaspora Corridors
- 02EhExchange Houses & FX Bureaus
- 03SaSME Accounts & Cross-Border B2B Payments
- 04FcFreelancer & Contractor Payout Platforms
- 05TmTreasury & Multi-Currency Cash Management
- 06EfEmbedded Finance & Partner APIs
- 07MeMarketplace & E-Commerce Seller Payouts
- 08IeImporters, Exporters & Trade Payments
- 09BaBanks Adding International Transfers
- 10PcPayments Companies Entering New Corridors
- 11FlFintechs Launching Their Own Brand
- 12MwMobile Wallets & Regional Money Transfer Apps
At its center is a cross-border money transfer platform: sender and receiver apps, multi-currency wallets, an FX rate engine for currency exchange that applies your configured spread before the sender confirms, and corridors modeled with their own rail, fee logic and rules. SEPA, SWIFT-alternative rails and a correspondent network are supported, with APIs, webhooks and partner access for embedded finance, and add-ons extend it to forward contracts, hedge tools and crypto. That makes one codebase a base for remittance apps, digital wallets, peer-to-peer transfers and business payouts alike.
For controls, it ships KYC and KYB onboarding, AML workflows, real-time transaction monitoring with review queues, fraud rules, role separation and an audit trail. The software itself holds no license of any kind: money transmitter, e-money or payment institution licenses belong to you or your licensed partner, as do your correspondent and payout-partner relationships and the liquidity you pre-fund on each corridor. What the platform adds is the evidence those relationships ask for, plus the settlement, reconciliation and FX spread controls your team needs to run every route at a margin.
06Under the hood
Step-by-Step Journey
How White Label Remittance Software Works - Transfer Flow, KYC & Money Movement
A good money transfer app looks simple to the customer. Underneath sits a structured flow: onboarding, verification, wallet setup, sending money, business tools, reporting and operator control. The Miracuves platform walks each customer from sign-up to real transfers on web and mobile.
Customer Journey - From Sign-Up to Daily Money Movement
Swipe · 6
- 1Create a Sender Account
Customers register on mobile or the web and select the profile that matches how they plan to send money.
- Start on Android, iOS or the web
- Sign-up begins with account details and an account type choice
- Personal, freelancer, business and other journeys branch off from onboarding
- 2Pass KYC and Activate the Wallet
Each customer completes the KYC check, and the multi-currency wallet switches on as soon as it clears.
- KYC or business verification gates account activation
- Verified customers get multi-currency wallets and see their balances
- Transfers, cards, payment requests and account actions unlock next
- 3Make an International Money Transfer
The home screen is where a customer chooses a recipient and sends real money across borders.
- Send through the wallet, a bank account or other methods you enable
- Save recipients so repeat payments are quicker to set up
- Use payment links, requests, cards and other everyday tools
- 4Pay Teams, Suppliers and Clients
Company and freelancer profiles unlock deeper tools over time, matched to the account type and what the customer wants to achieve.
- Freelancers raise invoices, manage clients and follow earnings
- Companies invite staff, run payroll and send bulk transfers
- Operators add approvals, controls and specialist finance tools as volume grows
- 5Stay Updated Through Notifications and History
Notifications, the transaction history and a clear activity view give customers a reason to return and send again.
- Customers check transactions, alerts, card spend and account history
- Recurring payments, scheduled transfers and spend tracking keep accounts active
- The platform becomes part of the regular finance routine for teams and operators
- 6Read Remittance Reports and Analytics
Customers and operators lean on reports and analytics to watch their money and make sharper calls as volume grows.
- Customers see activity, exports, statements and savings
- Companies and operators follow spend, payroll, cash flow and wider analytics
- Admin staff manage the platform through dashboards, reports and KPIs
Behind The Scenes
Platform Architecture - Wallet Ledger, Compliance Queues & Approvals
- 01Layer 01
Onboarding, Identity & Wallet Setup
Sign-up passes into identity checks, account-type logic, verification review and wallet activation, so every customer is verified before any money moves.
- 02Layer 02
Transfers, Payments & Wallet Ledger
Structured APIs run wallet actions, cards, links, payment requests and transfers, keeping balances, statuses, fees and transaction records consistent for customers and operators.
- 03Layer 03
Compliance, Risk & Review Queues
KYC results, screening through the sanctions list provider you connect, fraud signals and risk scores feed structured queues where staff review, escalate or block higher-risk customers, transfers and events.
- 04Layer 04
Operator Governance & Approvals
Operators review verification files, flagged transfers, compliance alerts, approvals and policy exceptions from one controlled console, with every action visible in the audit trail.
- 05Layer 05
Business Accounts, APIs & Integrations
Company teams, partner connections, API access, webhooks and organization-level governance run on scoped keys, event streams, permissions and outside connectivity layers.
- 06Layer 06
Monitoring, Logs & Analytics
Operators get the visibility they need for reporting, investigations and long-term control from platform metrics, API performance figures, transaction analytics, the state of background jobs and of each integration, exports and audit logs.
Technology
Remittance Platform Tech Stack - Flutter, Node.js, Postgres & Gateway APIs
Behind the apps, money transfer software needs well-structured APIs, controlled financial workflows, dependable data design, clean integration points and clear operational visibility. Miracuves builds on a modern architecture chosen for extensibility, governance and products with many user roles.
Core pieces include multi-currency wallets, an FX rate engine and payment gateway connectors, with banking, SEPA, correspondent and payout rails reached through the partners and payment providers you contract and fund. Live rails and live FX switch on once those agreements are in place.
Mobile & Web Apps
- Android & iOS from one shared Flutter codebase
- Responsive web dashboards for personal, business and admin users
- Screens that adapt to each role: customers, support staff and the operator console
APIs & Business Logic
- Modular APIs for transfers, business accounts, risk checks and admin work
- Structured to split into microservices as volume and scope grow
- Covers accounts, transactions and cards alongside auth, FX, notifications and admin controls
Ledger, Transactions & Audit Data
- Storage for accounts, wallets and customer records
- Structured records for transactions, ledgers and payments
- Indexing & query optimization for quick lookups, feeds & finance operations
- Connectors for the BaaS, banking and payout partners you sign with
- Transfer orchestration with FX conversion from the rate feed you choose
- Webhook handling, reconciliation and transfer status kept in sync
Hosting & Scaling
- Auto-scaling as transaction load grows
- CI/CD pipelines for safer, quicker releases
- Backups, recovery, and staging-to-production promotion
Edge Performance & Protection
- Fast global delivery of static files and web app assets
- DDoS mitigation and WAF rules at the edge
- Edge rules set to your own risk policy before live money flows
You receive the source code, so your own engineers can extend workflows, add integrations, connect partner systems and grow the platform without rebuilding it.
Build to Scale
Built to Scale - Transaction Volume & Multi-Currency Growth
A good launch is only the start. As volume grows, a money transfer platform has to carry more transactions, tighter governance, more integrations, deeper reports and dependable operational visibility. Miracuves organized the codebase for scale, control and long-term extension across customer, business, operator and partner workflows.
Structured for Rising Transfer Volume
Domain-based APIs and a multi-role design are built to absorb growth in wallet activity, transfers, reporting jobs, compliance events and admin work.
Designed to Degrade Gracefully
Optional integrations are designed to fail gracefully, so the core keeps working as scope widens and operational load climbs.
Visibility Into API & Integration Health
API performance metrics and integration health monitoring let your team track response times, failures and overall system health as volume rises.
One Backend Behind Every Surface
Web, mobile and the operator console all draw on the same backend capabilities, so customers, finance staff and operators work from consistent data every day.
Health Checks, Jobs & Resilience
You get health dashboards and API metrics, along with background job monitoring and integration health tracking, plus exposed metrics for your monitoring stack. Together they help you keep running and respond to issues sooner.
Room for Multi-Brand, Enterprise & Partner Growth
You can grow into enterprise, partner and multi-market deployments thanks to white-label configuration, multi-role access, API-led integrations and organization-level governance.
For Founders & CTOs
Start with a focused launch on a platform designed to grow into broader operations, firmer governance, deeper integrations and years of product evolution, with no rebuild from scratch later.
07Security and compliance
Security
Money Transfer Software Security - KYC, AML, Encryption & Access Controls
Running a money transfer platform means holding identity data, financial activity, compliance cases, transaction records and sensitive operator actions. Security, audit trails and governance are designed into every Miracuves remittance build from the start, not added later.
The software provides KYC and AML case tooling, encryption and role-based access. Money transmitter or e-money licenses, banking and payout partners stay with you, the operator.
- 01 · WorkflowProtected Money Flows & Role-Based Access
Security is designed in from the start, with strict authentication and authorization around money movement, admin, compliance and integration workflows.
- 02 · AccessSign-In Protection & Role-Based Access
MFA flows, session and device protections, trusted-device management, sign-in history, admin session tracking and role-based permissions cover both customer and operator surfaces.
- 03 · FraudFraud, Risk & Abuse Controls
Hooks for the sanctions screening provider you connect sit beside fraud analysis, risk scores, handling of flagged transfers, anomaly detection and suspicious-activity casework, with a review path whenever behavior looks higher risk.
- 04 · GovernanceCompliance Casework & Incident Handling
From the console, your admin and compliance staff handle KYC reviews, AML/CFT cases and suspicious activity reports, prepare regulatory filings, read audit logs, track incidents and apply policy-based controls; the filings themselves remain yours.
- 05 · StandardsBuilt to Recognized Security Controls
OWASP ASVS 5.0.0 is the build standard for the controls, which also come with a control map against NIST 800-53 Rev. 5, PCI DSS v4.0.1 and ISO/IEC 27001:2022. We hold no certificate; the operating entity is the one that gets certified.
- 06 · DataAudit Trails, Data Control & Retention Policies
Sensitive financial and admin actions leave an audit trail, and you set data retention rules, scheduled deletion jobs and how sensitive operational records are handled.
A Note for Operators: Identity checks, transactions, compliance and operator actions all need to be protected, auditable and tightly controlled. Miracuves gets you launched sooner without cutting corners on security or governance, while the hardening, licenses and partner agreements for live operation stay with you.
Discuss Security & Compliance With UsLicensing Disclaimer
Remittance Software Compliance - Software Scope, Licensing and Gateway Partners
This purchase is a software product; it does not include a money transmission license. The layer Miracuves supplies covers recipient management, KYC and AML queues, the operator console, audit trails, FX, fee and corridor rules, transfer and payout workflows, plus multi-currency wallets backed by ledgers. Issuing cards or account details, settling fiat and moving or holding customer money across borders are regulated activities. Someone licensed must carry those, either under your own company's authorization or through an integrated partner such as an Electronic Money Institution (EMI), sponsor bank, payment institution or money transmitter. The build connects to that partner’s APIs. It cannot replace the partner, and Miracuves does not act as one.
“Ready” means the architecture carries the controls a payments operator relies on: card data tokenized by the processor so no card numbers sit in the database, encryption of data in motion and in storage, segregated admin roles with role-based access, tamper-resistant audit logs and separate environments. Your own review of your environment, processes and hosting therefore begins from a codebase built around those controls instead of a rebuild.
What the Build Includes
Source code you own, covering role-based access, audit logs, queues for reviewing transactions, AML and sanctions-screening hooks, onboarding for KYC and KYB, recipient management, payout and transfer workflows, rules for corridors, fees and FX spread, plus wallets and ledgers across multiple currencies.
What a License Adds
Holding customer funds, moving money from one country to another, issuing cards and account details, fiat settlement, safeguarding balances and regulator reporting. That authority sits with your money transmitter, payment institution, EMI or sponsor bank partner, or with a license your own entity holds. Software cannot substitute for it.
PCI-DSS Boundaries Around Card Data
Payment tokens are what the platform stores, never primary account numbers, which leaves cardholder data inside the certified environment of your processor. That narrows the PCI-DSS assessment you face yourself, as far as your integration permits.
Each Corridor Decides the Route
Both ends of a corridor require licensing for money transmission. US operators typically need an MSB (money services business) registration with FinCEN, and also money transmitter licenses issued separately by each state. In the UK, FCA authorization comes as an EMI or in the form of an Authorized Payment Institution (API). Under the E-Money Directive and PSD2, EU operators hold either a payment institution license or an EMI license. Many operators often start by relying on a sponsor bank or a licensed partner instead. Check which route fits by asking that partner, or counsel who specializes in financial services. Legal, licensing and regulatory advice is not something Miracuves gives.
08Grow the platform
- International sends
- Balances per currency
- Business money tools
- Controls & audit
How add-ons work
- 1Compose your modules
Pick modules on day one or later on; the core is never rebuilt.
- 2Quoted per module scope
In writing, every module carries a separate scope and price.
- 3Arrives with the source
Same as the core, the source code is handed over and belongs to you.
Add-Ons
Remittance Software Add-Ons - FX Forwards, Crypto & Partner Integrations
The core platform Miracuves ships already covers wallets, transfers, invoicing, compliance queues, the operator console and integrations. To move faster, add modules for governance, partner programs, advanced finance and enterprise operations, either at launch or once your rollout grows.
Pause by hovering · drag to explore
- 01Governance & compliance
Deeper Compliance Review Workflows
Add extra review stages, stricter approval rules, country-specific verification handling and more operational checks for corridors with heavier supervision.
Regulated Regions · Compliance Tooling - 02Treasury tooling
FX Forwards & Hedging Tools
Bring in FX forward contracts and hedging workflows for customers or companies that need to plan ahead, manage rate exposure and see their risk.
Currency Exchange · Treasury Teams - 03Governance & compliance
Extended Approvals & Organization Governance
Give business and enterprise deployments richer approval chains, tiered access layers, organization controls and oversight across teams and roles.
Corporate Finance · Enterprise Accounts - 04Connectors & rails
Partner APIs, Webhooks & Embedded Finance
Grow the product with deeper partner connections, API-led workflows, webhook automation and embedded finance features for platforms built around outside systems.
Embedded Payments · SaaS Products
- 05Expansion & sub-brands
Referral & Rewards Module
Drive referral growth with shareable links, reward tracking and incentives tied to verified activity and completed onboarding.
Early-Stage Teams · Launch Pushes - 06Connectors & rails
Crypto, L2 & Cross-Chain Module
Add more specialized digital asset workflows, including L2 support, bridge-aware routing and wallets for BTC, ETH and USDT.
Digital Assets · Blended Products - 07Governance & compliance
Per-Corridor Rules & Regional Settings
Tailor the platform to each market with rules per corridor, configurable requirements, region-specific policies and local operating procedures.
Local Operators · Licensed Regions - 08Expansion & sub-brands
Multi-Brand / Multi-Tenant Setup
Operate several branded money transfer products on one shared codebase, each with its own branding, configuration, operational controls and rollout plan.
Resellers · Branded Operators
More Fintech Products
Building in Fintech? See the Rest of Our Digital Banking Lineup.
Miracuves builds its white label remittance software as a multi-currency remittance platform for sending money abroad, exchanging currency and handling cross-border payments.
01A neobank clone gives you a digital-first bank app for opening accounts, making payments, handling cards and automating money management.
Explore Solution
02The Revolut Clone delivers a digital banking app including multi-currency accounts, global payments, cards, crypto, investing and budgeting tools, all from one scalable codebase.
Explore Solution
03A banking solution gives you modular core banking, with accounts, transactions, payments and compliance tooling in a single stack.
Explore Solution
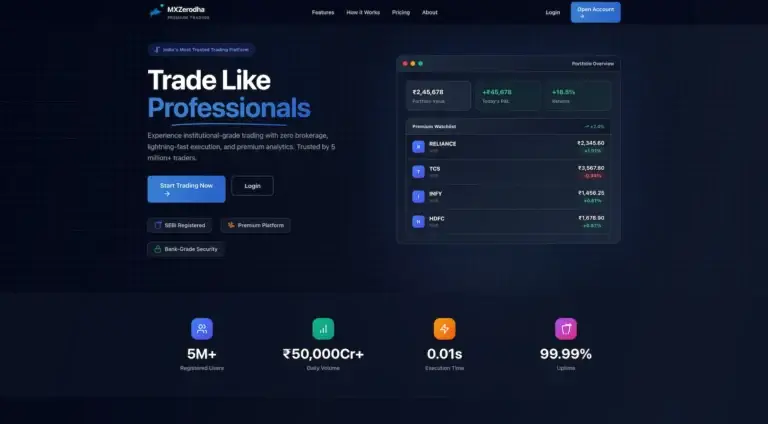
04A Zerodha clone is a stockbroking and trading platform for equities, derivatives and commodities, built around a discount-broker model.
Explore Solution09The business case
Market Benchmarks
Independent Benchmarks for Remittance and Payments Markets - 2025-2026 Data
The revenue models higher up on this page are our own writing, while the numbers that follow originate with other publishers: Wise, the Financial Stability Board, Remitly and the Reserve Bank of India. We repeat them exactly as released. Reading them shows an operator what listed incumbents earn for each dollar moved, what senders typically still pay, and how far volumes of card and instant payments have scaled.
$243.5bn Crossed Borders on Wise at 52bps
Wise's year closing 31 March 2026 saw US$243.5 billion move across borders, 31 percent higher than US$185.2 billion, and 18.9 million active customers. Take rate on that business dropped from 0.58 percent to 0.52 percent. Full-year results published 25 June 2026 added that 75 percent of Q4 payments worldwide finished in under 20 seconds.
On Average, a $200 Remittance Carries a 6.5% Cost
Published 9 October 2025, the Financial Stability Board's progress report on cross-border payments for the 2025 G20 sets the global average cost at 6.5 percent for sending US$200 in remittances and 4.3 percent for US$500, with both flat against 2024. Its conclusion: meaningful worldwide progress looks improbable on the timetable of the 2027 Roadmap.
Revenue Near 2.2% of $74.9bn in Remittances
Remitly filed its 2025 annual report on Form 10-K on 18 February 2026, and send volume reached US$74.9 billion, up 37 percent from US$54.6 billion, and revenue came to US$1,635.1 million, which is 29 percent higher. Revenue divided by send volume works out to roughly 2.2 percent; that ratio is arithmetic we performed on the reported figures. Active customers in the fourth quarter numbered 9.3 million.
India Recorded 6.0bn Credit Card Payments in 2025-26
In 2025-26, credit cards in India saw 60,238 lakh transactions with a value of Rs 23.6 lakh crore, as stated in the Annual Report 2025-26 of the Reserve Bank of India, which is dated 29 May 2026. The prior year's figures were Rs 21.1 lakh crore across 47,741 lakh transactions. The same report states that UPI made up nearly 86 percent of all retail payment transactions, and UPI volume grew 30 percent.
Wise Group plc, Wise Group plc reports Full Year 2026 Financial Results, regulatory news release, 25 June 2026 - investegate.co.uk
Financial Stability Board, G20 Roadmap for Enhancing Cross-border Payments: Consolidated progress report for 2025, 9 October 2025 - fsb.org
Remitly Global, Inc., Annual Report on Form 10-K for the year ended December 31, 2025, filed 18 February 2026 - sec.gov
Reserve Bank of India, Annual Report 2025-26, Chapter IX: Payment and Settlement Systems and Information Technology, 29 May 2026 - rbi.org.in
Every number here was reported by its publisher, and we pass it along as released. Only two items are ours: the Remitly ratio (arithmetic applied to reported figures) and the turning of 60,238 lakh transactions into about 6.0 billion. A figure of one lakh crore rupees is one trillion rupees. These data describe the market. They say nothing about the performance of whatever platform you build, and none of it amounts to a revenue forecast for your business.
Business Case
The Business Case for Owning Your Transfer Platform
Remittance software you own is more than a send-money screen. It becomes the operating layer for your corridors: wallets, FX rules, payout partners, KYC and AML queues and the finance console your team works in every day. Choose corridors where you hold a license or work with a licensed partner, price each one deliberately, and the platform becomes a lasting business asset rather than a rented tool billed per transfer.
- 01
Built for How Money Actually Moves
Sender and receiver flows, multi-currency wallets, corridors, FX rules, payout partners and an operator console cover the daily work of a transfer business, not one narrow feature.
- 02
Retail and Business in One Build
Individual senders, freelancers, SMEs, developers and your own compliance and finance staff each get a role, so one platform can serve several customer segments at once.
- 03
Repeat Senders Drive Retention
Remittance is habitual: the same sender pays the same recipient month after month. Saved recipients, wallets, payment links and clear tracking keep those customers coming back. Every send also carries a screening cost and pre-funding ties up capital, so margins are worth tracking route by route.
- 04
Room to Add Corridors and Partners
Each corridor is configured rather than coded, so once the license and partner are in place a new route is set up, not built. APIs and add-on modules extend it further.
- per-transfer fees you set by corridor
- the FX spread applied to each quoted rate
- card programs run with your issuing partner
- payment requests and collection links
- paid business plans for payouts, payroll and reporting
- metered API and partner access for embedded finance
- add-on modules such as forward contracts and premium tiers
Run well, owned remittance software can turn into:
- 01a money transfer brand customers trust
- 02the back office for your payouts and FX
- 03an API layer partners build their own flows on
- 04a record of every sender, recipient and business account you have earned
- 05the base for new corridors, treasury tools and enterprise clients
Illustrative scenarios only, not a forecast. Real results depend on the corridors you are licensed for, what your payout partners charge, how much liquidity you pre-fund and how often senders repeat.
Fees and FX spread on one or two community corridors, while a new operator proves trust, its compliance program and repeat sending.
Consumer remittances plus SME payouts and multi-currency wallets, growing through repeat senders and carefully added corridors.
Business accounts, partner APIs, treasury flows and larger volumes add upside, but only with licenses, partners and a mature compliance team on every route.
10Why Miracuves
How We Compare
Miracuves vs Other White Label Money Transfer Software Vendors
Most white label money transfer software is rented: a setup fee, then monthly or per-transaction charges, on the vendor's servers. Miracuves sells the platform once, hands over the source and deploys it in 6 days, so your database, your customer records and your margins stay with you. Licenses, payout partners and liquidity remain yours on either path.
The Case for Miracuves
- 01
Launched Within 6 Days
Start from a working white label remittance platform on your own cloud instead of a blank repository. Put the same questions to every vendor: who owns the source and the customer records, what happens the day payment stops, and where customer money sits.
- 02
Admin Panel Bundled
Corridor setup, FX rules, fee logic, reporting, monitoring and team roles live in the admin console from the first deployment.
- 03
KYC, AML & Audit Controls Built In
KYC, KYB, AML and fraud workflows plus an audit trail ship with the build. The licenses and partners they support remain the operator's.
- 04
Retail, Business & Partner Roles
Senders, freelancers, businesses, your compliance staff and API partners work in one platform with separate permissions.
- 05
Corridors Added by Configuration
Each corridor carries its own rail, fee logic and rules, so a new route is configured rather than rebuilt.
- 06
You Own It Outright
No per-transfer fee to us and no vendor kill switch. You get complete source with no encrypted files or license callback, on infrastructure you control.
How to Choose a White Label Remittance Software Development Company
A remittance software vendor should prove itself in a working product and a clean handover, not a sales deck.
What to look for Miracuves
- A demo you can log into Sender app, operator console and web app, each with a working login
- Source you actually own Complete, unencrypted source with no license callback or vendor kill switch
- Corridors as configuration Each corridor's rail, fee logic and rules are set in the console
- A client in production OrcaReserve's US senders now pay recipients in 50+ countries
- Cover after launch 60 days of guidance, 6 months of priority bug fixing and 12 months of updates
Walk away from any vendor who
- Bills per transfer or shares in your FX spread
- Hosts your customer records on its own servers
- Ships encrypted code that calls home for a license
- Claims its software replaces a money transmitter license
- Cannot show where a corridor's fee and FX rules are set
Compare a Platform You Own With Rented and Custom-Built Options
| Criteria | MiracuvesMiracuves Remittance Platform | Rented White Label Vendor | Custom Fintech Agency |
|---|---|---|---|
| Time to Deploy | 6 days for a standard deployment | Quick onboarding, but on the vendor's servers | Typically a multi-quarter program |
| What You Get | Sender and receiver apps, multi-currency wallets, corridors, FX rules, payout partner setup, KYC/AML queues and an operator console | Access to the vendor's features, not the code | Whatever the budget and spec cover |
| KYC, AML & Risk Controls | KYC, KYB, AML and fraud workflows plus an audit trail; screening providers your license requires are integrated to scope | The vendor's workflows; your own license is still required | Built from scratch at extra time and cost |
| Operator Console | Corridor, FX, fee, role and reporting controls in one admin console | Configured within the vendor's limits | Built as a separate workstream |
| Business & Partner Accounts | Retail senders, freelancers, businesses with KYB, and API partners | Depends on the plan tier you rent | Possible, scoped and priced separately |
| APIs & Integrations | APIs, webhooks, OAuth and partner access in the base build | Limited to what the vendor exposes | Usually added later in the project |
| New Corridors & Add-Ons | Corridors added by configuration; forward contracts, hedge tools and crypto / L2 as add-ons | Corridors follow the vendor's roadmap | Possible, at further cost and time |
| Pricing Model | $12,999 one time, source handed over, no per-transfer fee to us | Setup fee plus monthly or per-transaction fees | Hourly or milestone billing that grows with scope |
Release Notes
White Label Remittance Software Release Log - Version History & Updates
| Version | Date | What Changed |
|---|---|---|
| v2026.3 | Mar 2026 | Feature reference refreshed across sender app, web platform and admin console, describing the full multi-role money transfer scope. |
| v2026.1 | Jan 2026 | Scope of the product is set out across KYC and AML workflows, payment rails, wallets and transfers, identity and security, and governance and analytics. |
| v2025.9 | Jun 2025 | Security testing approach and evidence model set for the web app, APIs, sign-in flows, compliance modules, integrations, reporting and data exports. |
| v2025.8 | Feb 2025 | Business payout workflows, better notifications and upgraded reporting. |
Talk to our team
Launch Remittance Software You Own Outright
Bring your target corridors and partner setup. We will walk you through the live demo, scope the rollout and show what the 6-day deployment covers and what stays with you.
- Reply in 24 hrs
- Free consultation
- No per-transfer fees
- Source code handed over
11Learn more
Guides & Articles
White Label Remittance Software Insights Library
Guides, trends and case studies on building and running a cross-border money transfer business.
Product4 questions
01What is white label remittance software?
A money transfer platform you buy once and launch with your brand on it: sender and receiver apps, multi-currency wallets, corridors, FX rules, payout partner setup, KYC and AML queues and an operator console, with the source handed over. The Miracuves white label remittance software comes as Android and iOS apps, plus a web app and an admin console, deployed on infrastructure you control.
02Which parts are rebranded?
Everything your customers see carries your brand rather than Miracuves: app name, logo, colors, domains, app store listings, emails and receipts. Beneath that, the source code, the database and every customer record are yours.
03Can we change the design and add features later?
Yes. You hold the full source, so your team or ours can restyle screens and build new features. Corridors, fees and FX rules are already adjustable from the admin console without touching code. Add-on modules such as FX forwards and hedging tools, crypto and L2 wallets, per-corridor rules or a multi-brand setup can be added at launch or later.
04How does a remittance business earn on it?
You set per-corridor transfer fees and the FX spread, and can add card programs through your issuing partner, payment links, paid business plans, metered API access and add-on modules. We take no per-transfer fee, so fees and spread are yours in full.
Cost & rollout4 questions
05How much does white label remittance software cost in 2026?
The white label platform is $12,999 one time, with complete source, rebranding and deployment on your cloud included. Enterprise work such as custom integrations, extra modules or partner-led rollouts is quoted separately, and licenses, payout partners and liquidity are your own costs. Talk to Miracuves for a quote matched to your corridors.
06How soon do we go live?
A standard deployment takes 6 days on corridors you already have licenses and partners for. Regulated or partner-led Enterprise rollouts take 15+ days, and licensing and partner onboarding run on their own, much longer clock that you drive. The 6-working-day figure is published with its scope on the Miracuves facts page.
07How is this different from a white label money transfer subscription?
A subscription rents you the vendor’s platform: a setup fee, then monthly or per-transaction charges, with your data on their servers. Here you pay once, receive the source and run it on infrastructure you control, with no per-transfer fee to us. Either way, hosting, payout partners, KYC providers, liquidity and your licenses remain your costs.
08Can it run on our own cloud?
Yes. We provision it on your cloud account with the services, PostgreSQL database, monitoring, backups, domain and TLS configured, so data residency and access stay under your control. Hosting specifics are finalized during scoping.
Licensing & security2 questions
09Do I need a money transmitter license to operate?
Almost certainly, or a licensed partner. Money transmission is regulated at both ends of every corridor, so you obtain your own money transmitter, e-money or payment license in each jurisdiction you serve, or operate under a partner that holds one. Miracuves supplies the software, not permission to operate, and never holds customer funds. The routes differ by market (for example FinCEN MSB registration plus state money transmitter licenses in the US, FCA authorization in the UK, a payment institution or EMI license in the EU), so confirm yours with a licensed partner or financial-services counsel; Miracuves does not give legal or licensing advice.
10How is the platform secured, and is it certified?
It is built around encryption, role-based access, KYC and AML workflows, fraud rules and a full audit trail. Live fiat holding runs through integration with a licensed BaaS, EMI or sponsor bank partner that you select.
Stack, support & Miracuves9 questions
11Which tech stack does it use?
Flutter for the Android and iOS apps, Next.js for the web and admin surfaces, Express with TypeScript for the APIs, and Prisma with PostgreSQL for the ledger and data layer, with Stripe, webhooks and OAuth support for integrations.
12Do you provide support after launch?
Yes. Each deployment includes 60 days of technical support, 12 months of free updates and app publishing support. Longer maintenance or a dedicated team can be agreed while we scope your rollout. In full, every Miracuves deployment carries three cover periods from launch: 60 days of hands-on guidance from our platform team, 6 months of priority bug fixing and 12 months of ongoing product updates.
13Is the source code included with my purchase?
Yes. You receive the complete, unencrypted source with no license callback, so you own it outright and can extend it as your business grows.
14Why choose Miracuves to build white label remittance software?
Miracuves has delivered 9,000+ projects across a base of 6,000+ clients, and its catalog lists 90+ ready-made solutions that include remittance, neobanking and trading fintech platforms. OrcaReserve runs the US cross-border remittance platform it launched on this product, which makes it a production deployment. On the Miracuves facts page, each company figure is listed alongside its scope.
15Is ready-made white label remittance software better than custom development?
It usually is when speed and ownership both matter. This platform arrives with wallets, transfers, recipients, KYC and risk queues and an operator console already working, costs $12,999 once and is deployed in 6 days. Custom development is quoted in writing and starts from nothing, so it suits teams with a model no existing product covers. Many operators buy the ready-made base and commission only the corridor or partner work that is specific to them.
16What is the step-by-step process to launch my white label remittance software?
You start in the demo, then send a brief listing your corridors, payout partners, branding and the license or partner you will operate under. Miracuves applies your brand to the customer apps and the operator console, deploys everything on your cloud with its database, connects the rate, payment and KYC providers you choose and prepares the app store submissions. Deployment takes 6 days, and Apple and Google then check the apps on a timetable of their own, outside those days.
17How do funds move across borders on white label remittance software?
A sender funds a transfer from a multi-currency wallet in the sender app, the platform applies your corridor fees and FX spread, KYC and risk checks run, and your payout partner delivers the money to the recipient. Operators watch each step from admin visibility and audit trails. Live fiat holding runs through a licensed partner you select.
18Can banks and financial institutions use this white label money transfer software?
Yes. A bank or licensed institution can run it on its own cloud account with the complete unencrypted source, adding its own branding, corridors and payout partners. Money transmission is regulated at both ends of every corridor, so the institution brings its own license or a licensed partner, and the software supplies the operating platform.
19Does the remittance software support crypto wallets?
Crypto and L2 wallets are available as an add-on module, and they can be included at launch or added later. The base platform centers on multi-currency wallets, transfers, recipients, KYC and risk queues for fiat corridors. Add-ons are scoped separately, so you decide when your business needs them.
Disclaimer
Miracuves is an independent software development company. We are not affiliated with, connected to, sponsored by, or endorsed by Wise or any other money transfer, remittance or payments service.
Read our full Legal Notice & Disclaimer →“White label remittance software” describes a category of product, not any one company. Brand names appear elsewhere on this site only to describe the kind of platform being built and the terms buyers search for.
What we supply is software; permission to operate is not part of it. Responsibility for the payment, e-money or money transmitter licenses at both ends of each corridor you serve, or for operating under a licensed partner, stays with you. The same goes for correspondent and payout partners, safeguarding customer funds, reporting to each regulator, KYC, AML and sanctions screening. Advice on any of this is outside what we do.
The entire design and codebase is built by our own team. The product contains no code, design, graphics, or content originating from any third-party money transfer website or application. All third-party names and marks belong to their respective owners.