Key Takeaways
- Startups launching a digital banking platform should avoid treating onboarding, payments, transfers, cards, security, compliance workflows, and admin operations as separate product decisions.
- Common mistakes include overloading the first version with features, ignoring regulatory dependencies, creating complex onboarding, underestimating security needs, and failing to plan for transaction monitoring.
- A strong launch plan should prioritize reliable core banking workflows, clear user journeys, operational visibility, scalable infrastructure, and measurable activation before aggressive growth.
Launch Mistake Signals
- Launching too many features at once can complicate testing across account creation, KYC, card controls, money transfers, FX, notifications, transaction histories, and customer support.
- Weak authentication, unclear permission models, poor audit logging, limited fraud monitoring, and inadequate admin controls can create serious operational and security risks.
- Founders should also avoid overlooking banking partners, payment integrations, jurisdiction-specific requirements, reconciliation workflows, dispute handling, downtime planning, and customer support processes.
Founder Readiness Insights
- Before launch, teams should test onboarding completion, verification success, account funding, transfer processing, payment failures, card actions, notifications, refunds, and administrative intervention.
- Track activation rate, first-transaction conversion, failed transactions, support requests, verification drop-off, repeat usage, fraud alerts, system latency, and operational exceptions after release.
- Miracuves develops customizable digital banking platforms with onboarding, KYC workflows, accounts, cards, transfers, FX, transaction monitoring, security controls, analytics, and admin management.
Launching a digital banking platform is not just about creating a clean mobile app with account screens, transfers, cards, and wallet flows. For startups, the real challenge is building a product that can handle user trust, financial workflows, security, operational controls, regulatory expectations, and monetization without breaking under pressure.
Many fintech founders start with the visible layer first. They think about UI, branding, app screens, and feature lists. Those things matter, but they are not enough. A digital banking product needs strong backend logic, accurate transaction records, secure onboarding, admin control, provider integrations, audit trails, and a clear launch strategy.
This is where many startups make costly mistakes. They build too slowly, choose the wrong architecture, ignore compliance workflows, underestimate user verification, or launch without a strong admin dashboard. The result is usually delayed launch, higher development cost, weak user trust, and avoidable rework.
This guide explains the most important mistakes startups should avoid when launching a digital banking platform and how founders can make smarter product decisions from day one.
Why Digital Banking Platforms Fail Before They Scale
A digital banking platform usually fails before scale because the foundation was not designed for financial operations. It may look good in a demo, but once real users start onboarding, moving money, requesting cards, raising disputes, or triggering security checks, weak systems become visible.
For founders, this matters because fintech products carry a higher trust burden than many other app categories. A food delivery app can survive a late order. A video platform can survive a content upload delay. A financial platform cannot afford confusing balances, poor identity checks, missing transaction records, or weak admin visibility.
A launch-ready fintech product should be planned around four layers:
| Layer | What It Controls | Why It Matters |
|---|---|---|
| User layer | Signup, login, accounts, cards, transfers, wallet views | Builds user confidence and daily engagement |
| Financial workflow layer | Ledgers, transactions, FX, limits, fees, payment flows | Protects accuracy and monetization |
| Admin layer | Approvals, disputes, account actions, reporting, risk controls | Helps the operator manage the platform |
| Security and compliance layer | KYC, AML workflow support, audit logs, role-based access | Reduces operational and regulatory risk |
When one of these layers is weak, the platform becomes harder to manage, harder to trust, and harder to scale.
Mistake 1: Treating Digital Banking as Just Another Mobile App
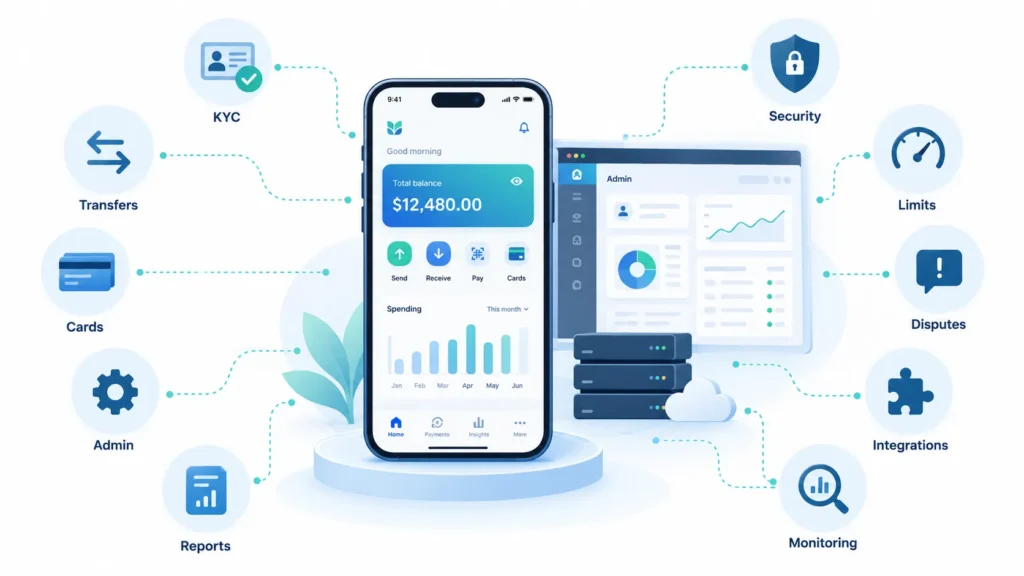
The biggest mistake startups make is treating digital banking like a normal consumer app. A banking platform is not only a frontend experience. It is a financial operations system.
A founder may say, “We need login, wallet, transfers, cards, and profile.” But the deeper questions are:
- How will account activity be recorded?
- How will failed transactions be handled?
- How will the admin team review suspicious activity?
- How will user identity be verified?
- How will limits, fees, and currencies be configured?
- How will disputes be tracked?
- How will provider integrations be monitored?
Without these answers, the product may look ready but fail operationally.
A stronger approach is to define the product as a complete fintech ecosystem. That means the customer app, web app, admin dashboard, backend APIs, payment integrations, identity workflows, reporting systems, and security controls should be planned together.
This is also where a ready-made digital banking foundation can help. Instead of building every module from zero, founders can start with a structured platform and customize it around their business model. For startups evaluating a faster launch route, Miracuves offers a ready-made digital banking platform foundation with source-code ownership, admin workflows, white-label branding, and 6-day deployment where applicable. Miracuves’ page states that the platform includes Android, iOS, web app, admin panel, source-code ownership, rebranding, and go-live support.
Mistake 2: Ignoring Compliance Workflows Until the End
Compliance should not be treated as something to “add later.” Digital banking products need compliance-aware workflows from the beginning because onboarding, identity checks, transaction monitoring, audit logs, and admin decisions all affect how the platform operates.
This does not mean the software alone makes a business legally approved in every market. Final compliance depends on jurisdiction, legal review, licensed partners, payment providers, banking infrastructure, and operating model. But the platform should support the workflows that compliance teams, financial partners, and internal operators usually need.
Important compliance-related workflows include:
- KYC onboarding
- AML workflow support
- User identity verification
- Business account verification
- Transaction monitoring hooks
- Suspicious activity flags
- Audit logs
- Admin approval history
- Role-based permissions
- Document review workflows
- Account freeze and review actions
- Dispute records
Identity proofing and enrollment are formal parts of digital identity guidance, and NIST’s current digital identity guidelines focus specifically on identity proofing and enrollment for authentication use cases. For startups, the practical lesson is simple: user verification should not be designed as a basic upload form. It should be planned as a structured onboarding workflow with review states, rejection reasons, resubmission paths, and admin visibility.
Mistake 3: Building Weak Onboarding That Creates Drop-Off or Risk
Onboarding is where fintech startups usually face two competing pressures. The platform must be easy enough for users to complete, but strong enough to support identity, risk, and account approval workflows.
If onboarding is too heavy, users drop off. If it is too light, the platform attracts risk. The mistake is choosing one extreme instead of designing a balanced onboarding flow.
A strong digital banking onboarding flow should include:
- Clear account type selection
- Phone and email verification
- Identity document submission where required
- Selfie or liveness verification where relevant
- Address or business verification where relevant
- Transparent approval status
- Resubmission options
- Admin review queues
- Risk-based checks
- Secure authentication
Founders should also think about the emotional experience. Users are sharing financial and identity information. If the app does not explain why information is required, how long review may take, or what happens after submission, trust drops quickly.
The best onboarding experience is not the shortest one. It is the clearest one.
Mistake 4: Choosing Features Before Defining the Business Model
Many startups create a long feature list before deciding how the platform will make money. That creates product confusion.
A digital banking platform can support different revenue models, but each model affects the product architecture. Subscription-led banking needs plan management and billing. FX margin requires currency conversion rules. Card revenue requires card lifecycle workflows. Business banking requires company accounts, permissions, and finance tools. BaaS-led monetization needs partner-ready APIs and account structures.
Common monetization models include:
| Revenue Model | What It Requires in the Product | Founder Risk If Ignored |
|---|---|---|
| Subscription plans | Plan tiers, billing, feature access, renewal logic | No clear recurring revenue path |
| Transfer fees | Fee rules, transaction classification, receipts | Revenue leakage or user confusion |
| FX margin | Currency rates, spread configuration, conversion history | Weak monetization on multi-currency activity |
| Card-related fees | Card issuance, limits, replacement, usage tracking | Incomplete card business model |
| Business accounts | Company profiles, roles, approvals, finance tools | Missed SME monetization opportunity |
| BaaS integrations | API readiness, provider mapping, partner workflows | Harder expansion and provider dependency |
The mistake is not having too few features. The mistake is building features that do not support the business model.
Before development, founders should answer: What will users pay for? What will businesses pay for? Which actions generate fees? Which features drive retention? Which workflows are needed for revenue control? A clear digital banking revenue model helps founders connect subscriptions, transfer fees, FX margins, card fees, and business account plans with the right product workflows.
Mistake 5: Underestimating the Admin Dashboard
The admin dashboard is one of the most important parts of a digital banking platform. Yet many startups treat it as a basic backend panel.
That is a serious mistake.
The admin dashboard is where the platform operator manages users, accounts, verifications, transactions, disputes, limits, notifications, reports, and risk actions. Without a strong admin layer, every operational issue becomes a developer dependency.
Founders should also review the core digital banking platform features before development because the strongest fintech products are not only judged by user-facing screens. They are judged by how well the platform handles KYC workflows, transaction visibility, audit logs, role-based access, limits, reports, and operational control.
A practical admin dashboard should help the operator:
- Review user onboarding
- Approve or reject documents
- Monitor transactions
- View account status
- Manage roles and permissions
- Track disputes
- Configure fees and limits
- Handle suspicious activity signals
- Export reports
- View audit logs
- Manage support tickets
- Control platform settings
FFIEC guidance on authentication and access for financial services highlights the importance of authentication controls, asset inventory, and transaction/audit logs for identifying suspicious activity and promoting accountability. For founders, this reinforces why admin access, permission control, and logs should be designed as core product features, not optional enhancements.
Miracuves’ digital banking product positioning also emphasizes admin control, KYC workflows, compliance controls, transaction monitoring hooks, audit logs, and role-based access as part of the platform foundation.
Mistake 6: Ignoring Transaction Accuracy and Ledger Logic
In fintech, the backend matters more than the screens. A beautiful interface cannot fix inaccurate balances or broken transaction records.
Startups sometimes assume transaction handling is simple: debit one wallet, credit another, show the status. In reality, financial workflows require careful handling of pending transactions, failed payments, reversals, refunds, settlements, limits, exchange rates, provider responses, and reconciliation.
Important transaction questions include:
- What happens if a transfer fails midway?
- How is a pending transaction displayed?
- How are reversals recorded?
- How are provider errors handled?
- How is transaction history synchronized?
- How are fees shown to users?
- How are admin actions recorded?
- How are disputes linked to transaction IDs?
A weak transaction system damages trust immediately. Users may forgive a design issue, but they will not forgive unclear money movement.
Founders should prioritize transaction reliability, ledger logic, reconciliation workflows, and auditability before adding advanced features.
Mistake 7: Selecting the Wrong Technology and Integration Path
Digital banking platforms usually depend on multiple systems: user apps, admin dashboards, payment gateways, KYC providers, BaaS providers, card issuing partners, cloud infrastructure, analytics tools, support systems, and notification services.
The mistake is choosing a technology path without considering future integrations.
A strong technical foundation should support:
- Secure API architecture
- Modular backend services
- Provider integration flexibility
- Scalable database design
- Role-based access control
- Encrypted data transfer
- Logging and monitoring
- Cloud deployment flexibility
- Mobile and web compatibility
- Clear documentation
Founders should avoid rigid systems that make every future change expensive. A digital banking platform will evolve as the business adds new markets, new providers, new account types, new currencies, new controls, and new monetization layers. When evaluating a fintech development team, startups should look beyond app screens and ask how the team handles ledgers, APIs, payment integrations, audit logs, provider flexibility, and post-launch support.
This is why source-code ownership is important. When the business owns the codebase, it has more control over integrations, customization, roadmap decisions, and long-term product evolution.
Mistake 8: Leaving Security as a Post-Launch Task
Security is not a launch checklist item. It is part of the product foundation.
Digital banking platforms handle sensitive user data, identity documents, account access, transaction history, payment flows, and admin actions. Security weaknesses can damage user trust, partner confidence, and operational stability.
For founders who want a deeper checklist, this fintech security controls guide explains how user protection, transfer security, access control, audit trails, fraud monitoring, and admin visibility support a safer digital banking launch.
Security planning should include:
- Encrypted data transfer
- Encrypted data storage
- Secure authentication
- Multi-factor authentication where relevant
- Role-based admin access
- Protected APIs
- Secure session management
- Audit logs
- Activity monitoring
- Payment security controls
- Access review processes
- Fraud monitoring signals
- Provider-level security review
For platforms that process or store cardholder data, PCI DSS exists to encourage and enhance payment card account data security and the broad adoption of consistent data security measures. Founders should confirm the exact scope of payment security responsibilities with their payment partners, card providers, and legal advisors.
The practical mistake is assuming that payment providers handle everything. Providers handle their part. The platform still needs secure access, clean data handling, controlled admin permissions, and proper operational logs.
Mistake 9: Trying to Build Everything From Zero Without a Launch Strategy
Some founders believe custom development from scratch is always the stronger choice. Sometimes it is. But for many startups, the bigger risk is spending months building the foundation before testing the market. Before choosing a build path, founders should understand the real digital banking development cost, including software, integrations, provider terms, compliance workflows, admin control, customization, and ongoing support.
A digital banking startup needs speed, but not at the cost of structure. The smarter question is not “custom or ready-made?” The smarter question is: What is the fastest safe route to a product that can be branded, controlled, integrated, and improved? For founders comparing launch paths, a white-label fintech platform vs custom build comparison can help clarify which route fits their budget, timeline, control needs, and validation strategy.
A ready-made approach can help when the founder wants:
- Faster market validation
- A working product foundation
- White-label branding
- Admin dashboard control
- Source-code ownership
- Core fintech workflows already structured
- Room for future customization
- Lower avoidable development risk
Miracuves helps founders move faster with a ready-made digital banking platform that can be deployed in 6 days, with source code, white-label branding, admin control, and customization support where applicable. The official Miracuves page lists 6-day go-live, 60 days of tech support, complete source codes, rebranding, white-labeling, app publishing support, and updates as part of the offering.
This does not mean every fintech product should avoid custom development. Deeply regulated, highly specialized, or bank-grade enterprise systems may need longer custom planning. But for startups validating a neobank-style business model, a ready-made foundation can reduce the delay between idea and market learning.
Mistake 10: Not Planning the Launch Market Clearly
A digital banking platform should not launch everywhere at once. Each market can have different customer behavior, provider availability, currency needs, onboarding rules, documentation expectations, and compliance requirements.
The mistake is building a generic product for “global users” without a specific first market.
A better launch strategy defines:
- Target country or region
- Primary user segment
- Retail or business banking focus
- Main currency flows
- Local payment methods
- KYC requirements
- Provider availability
- Expected transaction types
- Revenue model
- Customer acquisition channel
- Support process
- Compliance review path
A focused launch market helps the startup make better product decisions. For example, a platform for freelancers receiving international payments may need different workflows than a platform for local SME accounts. A strong fintech pre-launch and post-launch strategy also helps founders move from awareness to verified users, funded wallets, first transactions, retention, and revenue.
The clearer the first market, the easier it becomes to prioritize features.
Mistake 11: Copying a Product Pattern Without Owning the Differentiation
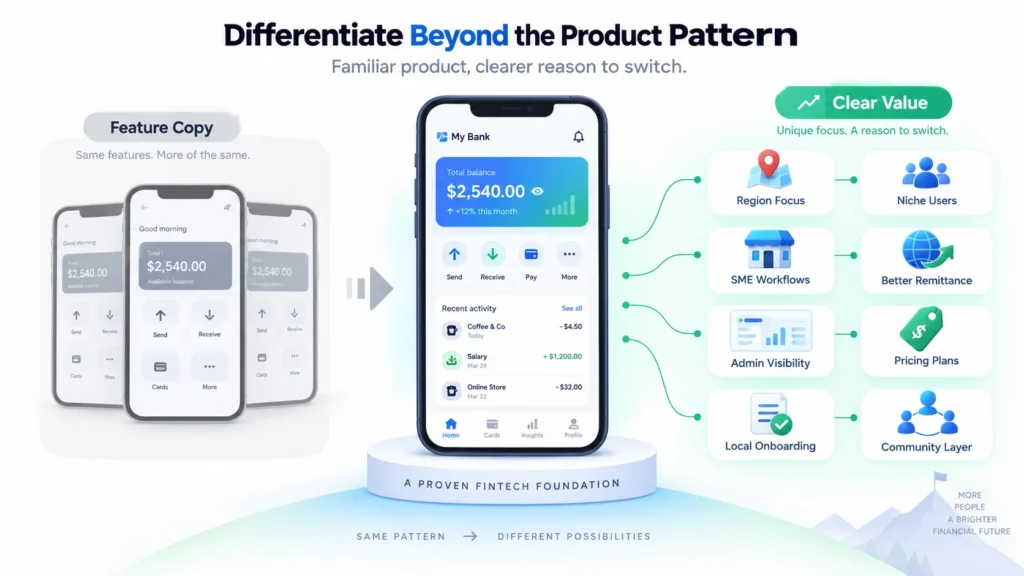
Founders often study successful fintech products because those platforms show what users already understand. That is useful. The mistake is copying the pattern without defining what will make the new platform different.
Differentiation does not always mean inventing something completely new. It can come from:
- Serving a specific region
- Targeting a niche user segment
- Offering better business account workflows
- Improving remittance experience
- Supporting freelancers or SMEs
- Adding stronger admin visibility
- Creating better pricing plans
- Building a localized onboarding journey
- Combining banking with community or marketplace features
The platform should be familiar enough for users to understand, but specific enough to create a reason to switch.
A founder should ask: Why will users trust this platform? Why will they open an account? Why will they keep using it? Why will they pay? What problem does this solve better for our chosen audience?
Without that clarity, the product becomes a feature copy instead of a business.
Mistake 12: Ignoring Support, Disputes, and Operational Workflows
Digital banking users need fast answers when money is involved. If a transaction is pending, a card is blocked, a transfer fails, or a verification is rejected, support quality directly affects trust.
Startups often launch with product features but forget operational workflows.
Important support and dispute workflows include:
- Ticket creation
- Transaction-linked support cases
- Verification rejection reasons
- Admin notes
- Status updates
- Refund or reversal request tracking
- Escalation paths
- User notifications
- Evidence collection
- Audit history
Support is not just a customer service layer. It is part of the financial operations layer.
A startup should design support workflows before launch because manual handling becomes messy as user volume grows.
Founder Decision Signals Before Launch
Speed
If the first product version will take too long to launch, the startup may lose market timing. A ready-made foundation can help founders validate faster while still keeping room for customization.
Control
If the platform operator cannot manage users, transactions, limits, disputes, and approvals from the admin dashboard, daily operations will become slow and developer-dependent.
Security
If authentication, access control, audit logs, and payment security are not planned early, the product may face trust and operational risks after launch.
Market Fit
If the product tries to serve every market from day one, feature priorities become unclear. A focused first market makes launch decisions sharper.
Digital Banking Launch Checklist for Startups
Before launching, founders should review the platform from a business, technical, compliance, and operational perspective.
| Launch Area | What to Check |
|---|---|
| Product strategy | Target market, user segment, account types, revenue model |
| Onboarding | KYC flow, verification states, document review, resubmission |
| Security | Authentication, MFA, encryption, API protection, access control |
| Transactions | Ledger logic, fees, failed payments, reversals, transaction history |
| Admin dashboard | User management, approvals, disputes, limits, audit logs |
| Integrations | BaaS, payments, cards, KYC, notifications, analytics |
| Monetization | Subscription plans, transfer fees, FX margin, card fees, business plans |
| Support | Ticketing, dispute handling, status notifications, escalation |
| Compliance support | AML workflow support, audit trails, reports, role permissions |
| Launch plan | First market, rollout scope, support process, post-launch roadmap |
This checklist should be used before development begins, not just before publishing the app.
How Miracuves Helps Startups Avoid These Mistakes
Miracuves helps founders launch digital banking platforms faster by starting with a ready-made, white-label product foundation instead of forcing every module to be built from scratch.
For fintech startups, this can reduce avoidable delay because core workflows such as account management, transaction views, admin controls, KYC workflow support, multi-currency logic, business modules, and source-code ownership are already part of the product direction. The platform can then be customized around brand identity, launch market, integrations, and monetization model.
The main advantage is not only faster delivery. It is decision clarity.
A founder can move from “What should we build first?” to “How should we customize this for our market?” That shift saves time, improves focus, and helps the team validate demand faster.
For startups evaluating a launch-ready fintech route, the Miracuves digital banking platform solution offers a practical path with white-label branding, admin dashboard control, source-code ownership, and 6-day deployment where applicable.
Final Thoughts
Launching a digital banking platform is not only a development project. It is a trust-building exercise.
Startups need to think beyond screens and features. The real foundation includes onboarding, compliance workflow support, transaction accuracy, security, admin control, monetization logic, provider integrations, support workflows, and market-specific launch planning.
The founders who avoid these mistakes are better positioned to launch faster, learn from users earlier, reduce rework, and build a platform that can grow beyond the first version.
A strong digital banking product is not created by copying features. It is created by combining a proven product structure with the right business model, operational controls, and market-specific execution.
FAQs
What are the biggest mistakes startups make when launching a digital banking platform?
The biggest mistakes include treating the platform like a basic mobile app, ignoring compliance workflows, building weak onboarding, underestimating admin controls, choosing the wrong tech stack, and launching without a clear monetization model.
Why is KYC important in a digital banking platform?
KYC helps verify user identity and supports safer onboarding. For startups, it should be planned as a complete workflow with document review, approval status, rejection reasons, resubmission, and admin visibility.
Do digital banking startups need AML workflow support?
Yes, digital banking startups should plan AML workflow support where relevant. This may include transaction monitoring hooks, suspicious activity flags, review queues, audit logs, and reporting support. Final obligations depend on the target market, legal structure, providers, and regulatory guidance.
Why is the admin dashboard important for fintech startups?
The admin dashboard gives the platform operator control over users, accounts, transactions, verifications, disputes, permissions, reports, and risk actions. Without it, routine operations become slow and difficult to manage.
Should startups build a digital banking platform from scratch?
Building from scratch can be useful for highly custom or deeply regulated products, but it may delay validation. A ready-made foundation can help startups launch faster, customize the experience, and test the market before investing in deeper expansion.
How can startups monetize a digital banking platform?
Common monetization models include subscription plans, transfer fees, FX margin, card-related fees, business account plans, premium features, and BaaS-enabled services. The right model depends on the target users and market.
How fast can Miracuves help launch a digital banking platform?
Miracuves offers 6-day deployment for its ready-made white-label digital banking solution where applicable. Deeper customization, integrations, compliance requirements, or market-specific changes may require additional planning.
What should founders check before launching a digital banking app?
Founders should review onboarding, security, transaction logic, admin controls, KYC and AML workflow support, payment integrations, user support, monetization logic, and the first launch market before going live.
Miracuves is an independent software development company. We are not affiliated with, connected to, sponsored by, or endorsed by any company or product named in this article.
Terms such as “X Clone” are used descriptively. It is how the software industry refers to building a platform with functionality comparable to a known service, and how clients search for it.
The entire design and codebase of our products is built by our own team. Our products contain no code, design, graphics, or content originating from any third-party website or applications.
All third-party names and marks referenced in this article are the property of their respective owners, referenced solely to identify the services discussed.